20 Changes to BC Real Estate Rules Since 2010 – and Why You Need a Mortgage Broker

Kelly Hudson • July 17, 2025

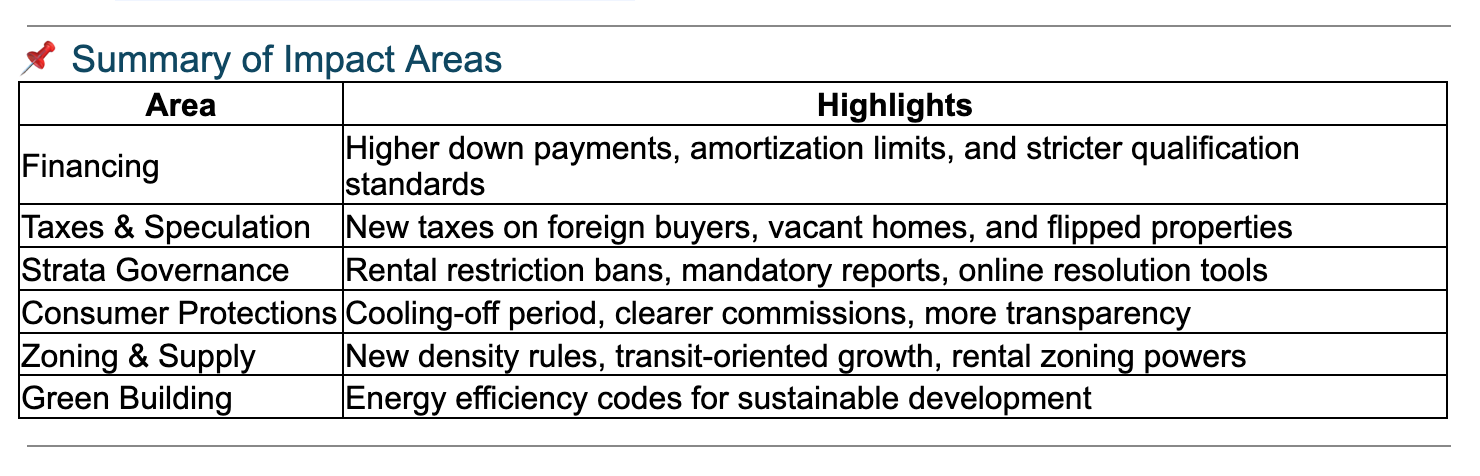
British Columbia’s real estate landscape has changed dramatically over the past 15 years. Since 2010, we've seen waves of new legislation, tax policies, zoning reforms, and consumer protections that affect how homes are bought, sold, financed—and lived in.


Whether you're a first-time homebuyer or a seasoned investor, keeping up with all these changes can feel overwhelming. That’s why working with a knowledgeable
mortgage broker has become more important than ever.


Here are
20 key real estate changes in BC since 2010—and how they affect you.


🏦 1. Stricter Mortgage Down Payment Rules

  • 2010: A 20% minimum down payment was introduced for rental properties.
  • 2011: The maximum amortization for insured mortgages dropped from 35 to 30 years.
  • 2012: For homes over $1 million, a 20% down payment became mandatory.


📉 2. Tiered Down Payment System Introduced

  • 2016: Buyers must put down 10% on the portion of a home’s price between $500,000 and $1 million. Insured borrowers must qualify at the higher benchmark rate.


🏘️ 3. Strata Rental and Age Restrictions Reformed

  • 2022: BC banned most rental restriction bylaws for strata buildings. Age restrictions are now limited to 55+ only.


📊 4. Depreciation Reports Mandated

  • July 1, 2024: All strata corporations with 5+ units must update depreciation reports every five years.


🌍 5. Foreign Buyer and Speculation Taxes

  • 2016: Aug. 2 A 15% Foreign Buyer Tax was introduced, later raised to 20% Feb. 20, 2018
  • 2018: Speculation and Vacancy Tax implemented in designated regions (Metro Vancouver, Victoria, Kelowna, Nanaimo, Central Okanagan).


🏷️ 6. Expanded Tax Zones

  • 2018 & 2023 & 2024 Foreign Buyer and Speculation Tax zones expanded to include more areas in BC


🏠 7. Homebuyer Cooling-Off Period

  • 2023: Buyers now have a mandatory 3-day “rescind” period after contract acceptance, offering time to reconsider (get financing, home inspection, appraisal etc.).


🧾 8. Home Flipping Tax Introduced

  • January 2025: Properties sold within one year of purchase may face a 20% provincial tax on profits, tapering to zero by year two.


📈 9. Realtor Commissions Under Review

  • 2024–2025: Ongoing lawsuits and policy scrutiny are prompting potential reforms to how commissions are structured.


🏛️ 10. End of Industry Self-Regulation

  • 2016: Real estate regulation shifted from industry-led to government-supervised under the Real Estate Services Act (RESA).


🏢 11. Updated Real Estate Services Rules

  • 2021–2022: Licensing, brokerage relationships, and realtor conduct rules were revised to improve consumer protection.


🌡️ 12. BC Energy Step Code Introduced

  • 2017: New energy-efficiency standards aim for all new homes to be net-zero ready by 2032.


🚫 13. Elimination of Single-Family Zoning

  • 2023–2024: Municipalities can no longer enforce single-family-only zoning. Multiplex and infill housing is now permitted in urban areas.


🚆 14. Density & Parking Near Transit

  • 2023–2024: Provincial rules increased allowable density near transit hubs and removed minimum parking requirements.


🏨 15. Stricter Short-Term Rental Rules

  • 2023–2024: Airbnb-style rentals are restricted or banned in many urban areas unless the unit is a principal residence.


🛖 16. Single-Stair Apartments Now Allowed

  • 2023–2024: Low-rise apartment buildings can now use single-staircase construction, lowering development costs.


📈 17. No Public Hearings for Code-Compliant Projects

  • 2023–2024: Projects that already meet zoning and building code can bypass public hearings to accelerate approvals.


🏙️ 18. Municipal Rental-Only Zoning Powers

  • 2018 & 2023: Cities can enforce rental-only zoning and monitor housing supply more closely.


🌾 19. Farmland "Monster Home" Limits

  • 2018–2021: Principal dwellings on ALR land are limited to 500 m², with rules around secondary dwellings tightened.


🏘️ 20. Strata Disputes Handled by Civil Resolution Tribunal (CRT)

  • 2016: The CRT gained authority to resolve strata and small claims disputes online—streamlining resolution for owners and tenants alike.
Why You Need to Work with a Mortgage Broker

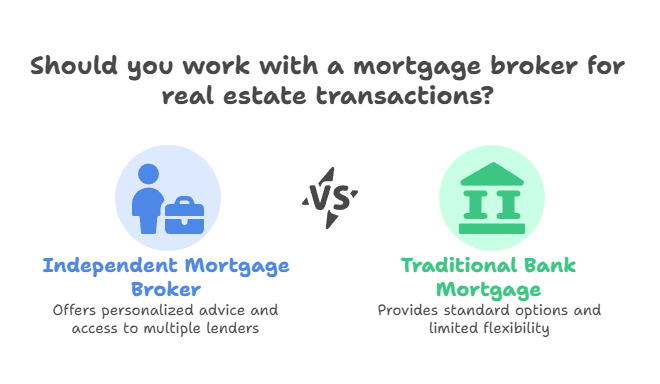
The last 15 years of real estate reform in BC haven’t just affected home prices—they’ve reshaped how homes are bought, sold, and financed. That’s why working with a professional mortgage broker isn’t just helpful—it’s essential.


✅ Expert Guidance

We stay up to date on every regulatory change—from the new flipping tax to strata law reforms—so you don’t have to. We’ll explain what matters and how it affects your financing.


💡 Tailored Mortgage Solutions

Every buyer has a different financial picture. We analyze your income, down payment, credit, and goals to match you with lenders that align with your unique situation—even when guidelines are shifting.


💰 Maximize Affordability

We help you navigate high down payment thresholds, mortgage stress tests, and short amortization periods to find strategies that keep your monthly payments affordable.


💼 We Advocate for You

Whether you're a first-time buyer, upsizing, or purchasing an investment property, your broker negotiates on your behalf and protects your interests.


Conclusion

With everything from zoning rules to tax policies evolving rapidly in BC, having a mortgage broker on your team means you’re not navigating it alone. You gain clarity, confidence, and access to the best possible mortgage solutions—so your real estate decisions are informed and strategic.


Need help navigating mortgage financing for BC’s ever-changing real estate market?


Let’s talk about how I can guide you through today’s rules—and help you plan for tomorrow.
Kelly Hudson
MORTGAGE ARCHITECTS
RECENT POSTS 

Reverse mortgage ad with smiling couple, house, flowers, and question marks about using home equity
By Kelly Hudson • October 9, 2026
For many Canadians, their home is their biggest financial asset. After years of homeownership, they may have paid off most (or all) or all their mortgage and built a lot of equity in their home. The problem: You can own a valuable home and still struggle to pay your monthly bills. You've probably heard the phrase “house rich and cash poor.” This is exactly what it means. For Canadian homeowners aged 55 and older, a reverse mortgage is one option worth looking at. It's definitely NOT the right solution for everyone. But for some homeowners, it can provide extra cash while allowing them to stay in the home they love. What Is a Reverse Mortgage? A reverse mortgage allows homeowners 55+ to access some of the equity in their home without selling it. Unlike a regular mortgage, you don't normally have to make monthly mortgage payments. Instead, interest is added to the amount you borrowed, so the balance grows over time. The mortgage is typically repaid when the home is sold, the homeowners permanently move out, or the last homeowner dies. And one of the biggest misconceptions I hear? The bank does NOT own your home. You do. You stay on title and continue to own your home. The money you receive is also generally tax-free because you're borrowing the money - it's not income. What Does “House Rich, Cash Poor” Look Like? Let's say you've lived in your home for 30 years. Your mortgage is paid off and your home is now worth $1 million. Sounds pretty good, right? But your retirement income may come from CPP, OAS, a pension and your savings. At the same time, groceries, property taxes, insurance, utilities and everything else seem to keep getting more expensive. So, while you may have hundreds of thousands of dollars in home equity, your monthly budget can still feel tight. You have the money. It's just tied up in your house. A reverse mortgage is one way to access some of that equity without having to sell and move. What Could You Use the Money For? There are generally no restrictions on how you use the money. Everyone's situation is different, but I've seen homeowners consider a reverse mortgage to: Pay off an existing mortgage, credit cards or other debts Add to your monthly retirement income Make home repairs or accessibility upgrades so you can stay in your home longer Pay for in-home care Help children or grandchildren financially Cover unexpected expenses or create an emergency fund Depending on the product, you may also have choices about how and when you receive the money. You don't necessarily have to take everything at once. Why Not Just Sell and Downsize? This is usually one of the first alternatives we talk about. Downsizing can make perfect sense—but it's not always as easy or as inexpensive as people think. A smaller home or condo can still be expensive, especially in many BC communities. Then add real estate commissions, legal fees, moving expenses, strata fees and other costs. And there's another part of this decision that has nothing to do with numbers. Your home is more than an asset on a balance sheet. Maybe you've lived there for 30 years. Your friends are nearby. You know your neighbours. Your doctor, family and community are close. Maybe you simply love your home and don't want to move. For many retirees, being able to stay in their home is an important part of their retirement plan. So... What's the Catch? There isn't any free money here. Reverse mortgage rates are typically higher than traditional mortgage rates. And because you aren't making regular mortgage payments, the interest gets added to the amount you borrowed. That means the amount you owe grows over time and the equity left in your home can decrease. There can also be appraisal, legal, setup and closing costs. Depending on the mortgage and when you repay it, there may also be a penalty. And remember—you still own the house. That means you're still responsible for maintaining it, keeping it insured and paying the property taxes. That's why it's important to look beyond the interest rate and understand the long-term costs. What About My Children's Inheritance? This is a conversation worth having with your family. A reverse mortgage will normally mean there is less equity left in your home for your estate. For some homeowners, leaving as much as possible to their children is extremely important. Others look at it differently. They would rather use some of the equity they've spent decades building to make their own retirement more comfortable. And some parents decide they'd rather help their children or grandchildren now , while they're still here to see them enjoy it (i.e. a gifted down payment). There's no right or wrong answer. It's your home, your equity and your decision. Reverse Mortgage or Home Equity Line of Credit (HELOC) ? A HELOC is another way to access the equity in your home. But there's an important difference. With a HELOC, you need enough income to qualify, and you'll need to make monthly payments. That can be difficult for someone who is retired and has a valuable home but limited monthly income. A reverse mortgage works differently because it's designed for older homeowners. One option isn't automatically better than the other. Maybe a HELOC makes more sense. Maybe refinancing makes more sense. Maybe a reverse mortgage does. It depends on your income, age, equity, monthly cash flow and, most importantly, what you're trying to accomplish. Is a Reverse Mortgage Right for You? 
Infographic on Canadian mortgage lending ratios, with house icons, GDS, TDS, and “How Much Mortgage Can You Afford?” text
By Kelly Hudson • September 16, 2026
If you're thinking about buying a home in BC, one of the first questions you probably have is: How much mortgage can I qualify for? Your income is certainly important, but it isn't the only number a mortgage lender looks at. Lenders also consider your debts, credit history, down payment, property costs and something called your mortgage lending ratios . The two ratios you'll hear about most often are GDS (Gross Debt Service) and TDS (Total Debt Service) . The names sound complicated. The math really isn't. Understanding how GDS and TDS work can give you a much better idea of what you may qualify for — and why two people earning the same income could qualify for very different mortgage amounts.