Kelly Hudson

MORTGAGE ARCHITECTS

LET’S WORK TOGETHER TO GET YOU THE BEST MORTGAGE AVAILABLE

LET'S TALK

BRIANNA & THOMAS

Happy Clients

As first-time home buyers we had a lot of questions regarding the mortgage process and Kelly did a fantastic job in helping us understand everything.  We highly recommend Kelly to anyone looking to purchase a home!
Hi, I’m Kelly — Your Mortgage Broker 😊


I’m a Richmond-based Mortgage Broker helping clients throughout the Lower Mainland and across BC.  For more than 12 years, I’ve helped people understand their mortgage options and make confident, informed decisions about one of the biggest financial commitments they’ll ever make.


Buying a home can be exciting — and a little nerve-racking! My job is to simplify the mortgage process, educate you along the way, so you can choose a mortgage that makes sense for your life and your finances.


Don’t Be Blinded by the Rate


A great mortgage is about much more than simply finding the lowest interest rate.

  • I specialize in Mortgage Intelligence — helping you understand how mortgages work, what lenders are looking for, and, just as importantly, what you should be looking for in a mortgage.

Every mortgage needs to balance four key priorities:

  • Lowest overall cost
  • Comfortable monthly payment
  • Maximum flexibility
  • Lowest risk

The fine print in a mortgage contract can sometimes matter far more than a slightly lower rate. Penalties, prepayment privileges, portability, restrictions, and flexibility can potentially cost — or save — you thousands of dollars.


Rates may be #1 and #10 on your list.

  • My job is to help you understand the other eight things in between.

The Earlier We Talk, the Better


In a perfect world, I’d love to meet you 3 months to 3 years before you plan to buy a home.


Why so early? Because good mortgage planning can start long before you find the perfect property. We can look at your income, credit, debts, down payment, and future goals and put together a realistic homeownership game plan.


And if you're ready to buy now? That's okay too!  😁😁😁


How I Can Help


Whether you're buying your first home or have owned property for years, I can help with:

  • First-Time Home Purchases — understand what you can afford and how the mortgage process works
  • Purchases & Move-Ups — find financing that fits your next stage of life
  • Mortgage Renewals — compare your lender's offer with other available options
  • Refinancing — access equity for renovations, investments, or debt consolidation
  • Rental & Investment Properties — financing for revenue properties and second homes
  • Reverse Mortgages — helping homeowners 55+ access equity in their home to live life on their terms

For a typical mortgage, my services are FREE to you because I'm paid a finder's fee by the lender, when your mortgage funds.


A Little About Me: Richmond has been home for more than 45 years. When I'm not talking about mortgages, you'll usually find me spending time with my husband George and our two rescue poochies, Sophie & Sam.

My Process is Simple.


Get in Touch

Get in touch with me however you feel comfortable. I will answer all your questions and provide you with counsel, all without any pressure.

 Choose a Solution

Once we've had a chance to go over your financial situation, I will outline all your mortgage options, and you can make the best choice for you.

Enhance your Lifestyle

With your new mortgage in place, you can get on with living your life! I'll always be there if you have any questions in the future!

Want to get started right away? 

APPLY NOW
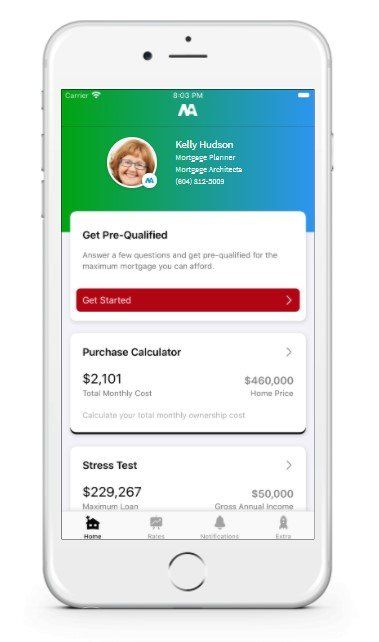
Download My Mortgage Toolbox


Download My Mortgage Planner using my personal install buttons so you can get exclusive access to all the premium features to help you plan your mortgage.
Renewal

Up for renewal? Here are 5 steps to follow to ensure a smooth process.

Refinance

Need to refinance? Here is a plan that you can follow.

Take the stress out of mortgage financing.


LET'S TALK

Simple mortgage advice, honestly given!
Infographic on Canadian mortgage lending ratios, with house icons, GDS, TDS, and “How Much Mortgage Can You Afford?” text
By Kelly Hudson September 16, 2026
If you're thinking about buying a home in BC, one of the first questions you probably have is: How much mortgage can I qualify for? Your income is certainly important, but it isn't the only number a mortgage lender looks at. Lenders also consider your debts, credit history, down payment, property costs and something called your mortgage lending ratios . The two ratios you'll hear about most often are GDS (Gross Debt Service) and TDS (Total Debt Service) . The names sound complicated. The math really isn't. Understanding how GDS and TDS work can give you a much better idea of what you may qualify for — and why two people earning the same income could qualify for very different mortgage amounts.
By Kelly Hudson May 12, 2026
If you’re buying a condo, townhouse, or bare-land strata property in BC, there’s one document many buyers overlook: the depreciation report. Strata depreciation report requirements - Province of British Columbia And honestly… it’s one of the most important documents you can review before buying. I see this all the time with clients. Some buyers carefully review it. Others quickly skim through it just to “check the box.” But this report can affect: your mortgage approval future repair costs special levies insurance and how stressful ownership may become later So, let’s break it down in simple, real-world language.
By Kelly Hudson March 6, 2026
Decisions relating to real estate can have significant financial and legal consequences. Before deciding how to share ownership of what is likely one of the largest investments of your life, I recommend consulting a real estate lawyer. Many Canadians purchase property together — including spouses, common-law partners, family members, friends, and business partners. Because ownership structure affects estate planning, taxes, creditor exposure, and control over the property, it’s important to understand your options before you sign. In Canadian property law, there are two primary forms of co-ownership: Joint Tenancy Tenancy in Common While these terms may sound similar, they have very different legal and financial effects — particularly if one owner dies, sells their interest, separates, or faces creditor claims.
By Kelly Hudson February 18, 2026
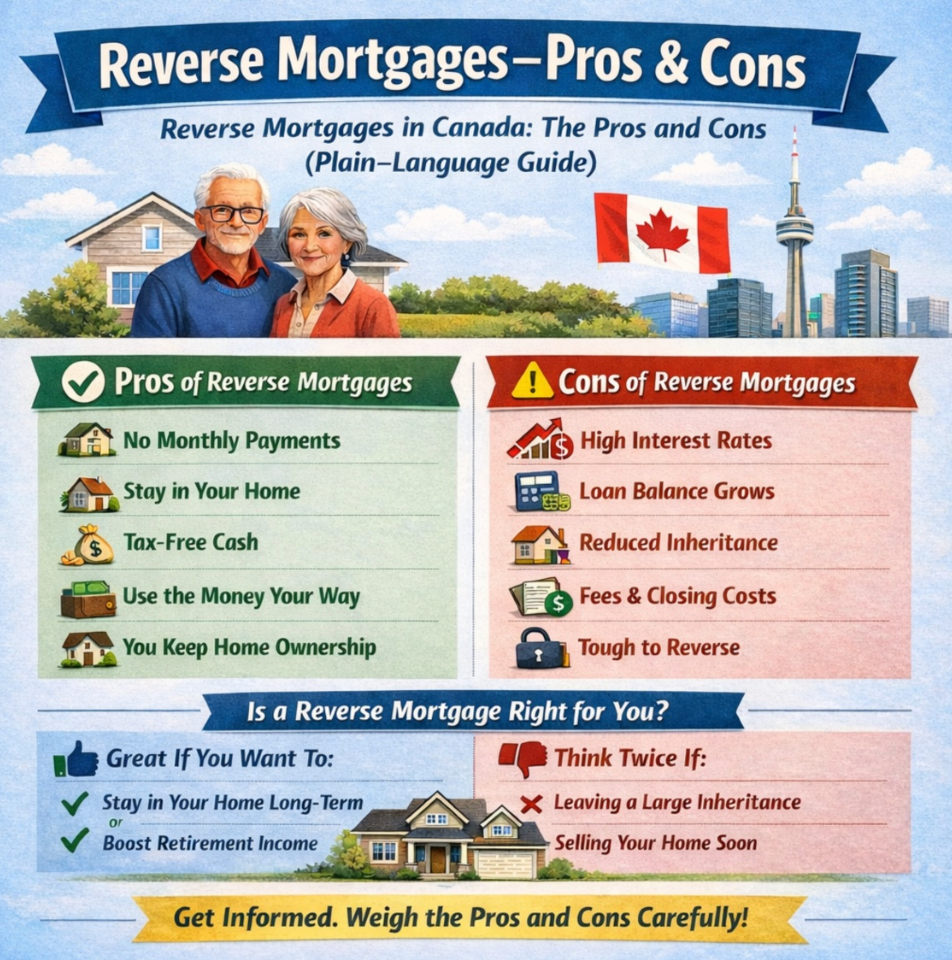
If you’re 55 or older and own your home, chances are you’ve heard about reverse mortgages. Sometimes they’re described as a “retirement lifesaver.” Other times they sound risky or confusing. The truth? They’re neither magical nor terrible. They’re simply a financial tool — and like any tool, they work well in some situations and not so well in others – EDUCATION is the key! Let’s break it down in plain English. So… What Is a Reverse Mortgage? A reverse mortgage allows you to borrow money against the value of your home — without making monthly mortgage payments. Instead of you paying the lender every month, the interest gets added to the balance. The loan is typically repaid when: The home is sold You move out permanently Or you pass away In Canada, reverse mortgages are currently offered by: HomeEquity Bank (CHIP Reverse Mortgage) Equitable Bank Bloom Financial You still own your home and your name stays on title. That part often surprises people. How It Works (Simple Version) To qualify: You must be 55 or older You must own your home (you can still have a regular mortgage — it just needs to be paid out) You can usually borrow up to about 55% of your home’s value (the older you are, the more you may qualify for) You don’t make monthly payments. But you must continue to: Pay property taxes Keep home insurance in place Maintain the home The money you receive is tax-free. It can come as: A lump sum Monthly advances Or a combination of both That flexibility is one reason many retirees like this option. Why Do People Consider Reverse Mortgages? Most of the homeowners I speak with aren’t looking for luxury spending money. They’re trying to solve real life situations: Covering rising living costs Paying off debt before retirement Managing health or care expenses Staying in their home longer Helping adult children with a down payment For many Canadians, their house is their largest asset — but it doesn’t create monthly income. A reverse mortgage turns some of that home equity into usable cash. The Pros (The Reasons People Like Them) 1. No Monthly Mortgage Payments This is the big one. If you’re living on CPP and OAS, removing a monthly mortgage payment can dramatically reduce stress. Cash flow improves immediately. 2. You Can Stay in Your Home Most people I meet don’t want to move. They love their neighborhood. Their friends are nearby. Family visits often. A reverse mortgage can allow you to age in place instead of selling before you’re ready. 3. The Money Is Tax-Free Because it’s borrowed money — not income — it does not affect: Old Age Security (OAS) Guaranteed Income Supplement (GIS) That’s a major advantage compared to withdrawing from investments. There are no rules about spending. Some clients use the funds to stay in place – health care at home. Some clients renovate. Some travel. Some gift funds to children. Some simply create a safety cushion. It’s your equity – you decide. 5. You Keep Ownership The bank does not own your home. As long as you live in your home, maintain it, insure it, and pay property taxes — you own your home and can stay. 6. No Negative Equity Guarantee In Canada, reverse mortgages include protection so that you (or your estate) will never owe more than the home is worth — even if property values decline. That protection matters.
READ MORE POSTS