How LOW Can Mortgage Rates Go???

Kelly Hudson • July 21, 2015

How LOW Can Mortgage Rates Go???

Somewhat expectedly , on July 15 the Bank of Canada (BOC) cut their Benchmark Interest Rate for a second time this year by 25 basis points, down from 0.75% to 0.50%.

There is a direct correlation between the BOC’s key interest rate and consumer “Prime Rate” which affects everything from variable rate mortgages to lines of credit.

Prior to July 15 the consumer Prime Rate with all major financial institutions was 2.85%.

Minutes after BOC lowered the rate, TD was first out of the gate first to say that they would only be dropping their Prime Rate down to 2.75% – which only reflects a 10 basis point cut, not the full 25 basis points.

The other major banks, (Scotia, RBC, BMO etc.) lowered their prime rate by 15 basis points (still not the full 25 basis points) and TD followed suit.

If you recall, back in January when the BOC cut their key rate from 1.00% to 0.75%, TD was the first out of the gate again, and they stated that they wouldn’t be cutting their Prime Rate at all! However within a few days, RBC and Scotia both announced a cut on their Prime down to 2.85%, and TD quickly followed suit.

What should you do with your mortgage? 

In my opinion, variable rate mortgages (VRM) are still your best bet – for a few reasons:

  • A typical discount on a 5 year VRM is Prime -.65%
  • The cut to Prime rate by all lenders lowers your interest costs and results in a lower payments.

Furthermore, the outlook for the BOC’s Benchmark rate remains low. BOC Governor Steven Poloz stated in his announcement July 15 that “The Bank anticipates that the economy will return to full capacity… in the first half to 2017.” This timeframe was pushed back from his previous statement that the Canadian economy would be back to full capacity by the second half of 2016.

Even if we assume no further rate cuts will happen over the balance of 2015; we’re unlikely to see a rate increase in the short to medium timeframe.

It’s a great time to get your mortgage or line of credit paid down!

Some interesting things to consider:

  • One major effect the rate cut had was an immediate drop in the Canadian dollar. The loonie ended the day, July 15 at 77.40 cents US, down 1.09 cents after the rate cut. Today, July 20 the dollar down further at 76.94 cents US.
  • This rate cut will also continue to lead to further speculation of an over-valued housing market. Always a hot topic in Canada.

The Globe and Mail wrote a good piece about this on July 15: Five things to watch after the rate cut .

As always, I am available at any time to discuss, plan, help, and listen to your questions, concerns, and feedback.

Let’s have a chat to discuss your next steps to home ownership.
Kelly Hudson

Mortgage Expert

Mortgage Architects

Mobile 604-312-5009  

Kelly@KellyHudsonMortgages.com

www.KellyHudsonMortgages.com

Kelly Hudson
MORTGAGE ARCHITECTS
RECENT POSTS 

By Kelly Hudson • November 16, 2026
The Pros, Cons & Mortgage Risks Every Homebuyer Should Understand Imagine finding a home you love at a price that seems too good to be true. Then you notice the listing says “Court-Ordered Sale.” Is it a bargain? Is something wrong with the property? Can you still get a mortgage with only 10% down? Buying a court-ordered home in British Columbia can be a great opportunity, but there are risks you need to understand BEFORE making an offer! What Is a Court-Ordered Sale? A court-ordered sale happens when a BC court becomes involved in selling a property. This often happens when homeowners fall behind on mortgage payments and the lender begins foreclosure proceedings. It can also happen because of divorce, estate disputes, or other legal matters. Unlike a regular home sale, a judge may need to approve the purchase before it becomes final. This adds another step and possibly more competition. The Pros: Why Buyers Are Interested Potential Bargain: Some properties are listed at attractive prices. However, competing buyers can push the final selling price higher. Less Emotional Negotiating: Lenders are generally focused on recovering their money rather than negotiating based on personal feelings. Opportunity to Build Equity: Buying a home for $700,000 when similar properties are worth $750,000 could mean instant equity. But repairs and unexpected expenses can quickly reduce those savings. The Cons: What Could Go Wrong? 1. Buying “As Is, Where Is”. The seller generally won't guarantee the property's condition or pay for repairs. You could discover missing appliances/cupboards, roof leaks, plumbing problems, electrical issues, holes in the walls or mold after moving in. Always arrange a home inspection! 2. Another Buyer Could Beat Your Offer Even if the seller accepts your offer, another buyer may submit a better offer at the court hearing. You could spend money on inspections, appraisals, and legal advice but still lose the property. 3. Unconditional Offers In regular purchases, buyers often include conditions called subjects, such as financing, inspections, and reviewing strata documents. For court-ordered sales, these conditions generally need to be satisfied or removed before the court hearing. Once the court approves your unconditional offer, you're legally committed to completing the purchase. IMPORTANT: BC's usual three-business-day Home Buyer Rescission Period doesn't apply to purchases made under a court order. 4. Unexpected Costs and Delays Court dates, property access, repairs, and occupants who haven't moved out can create unexpected problems. Always keep extra savings available!
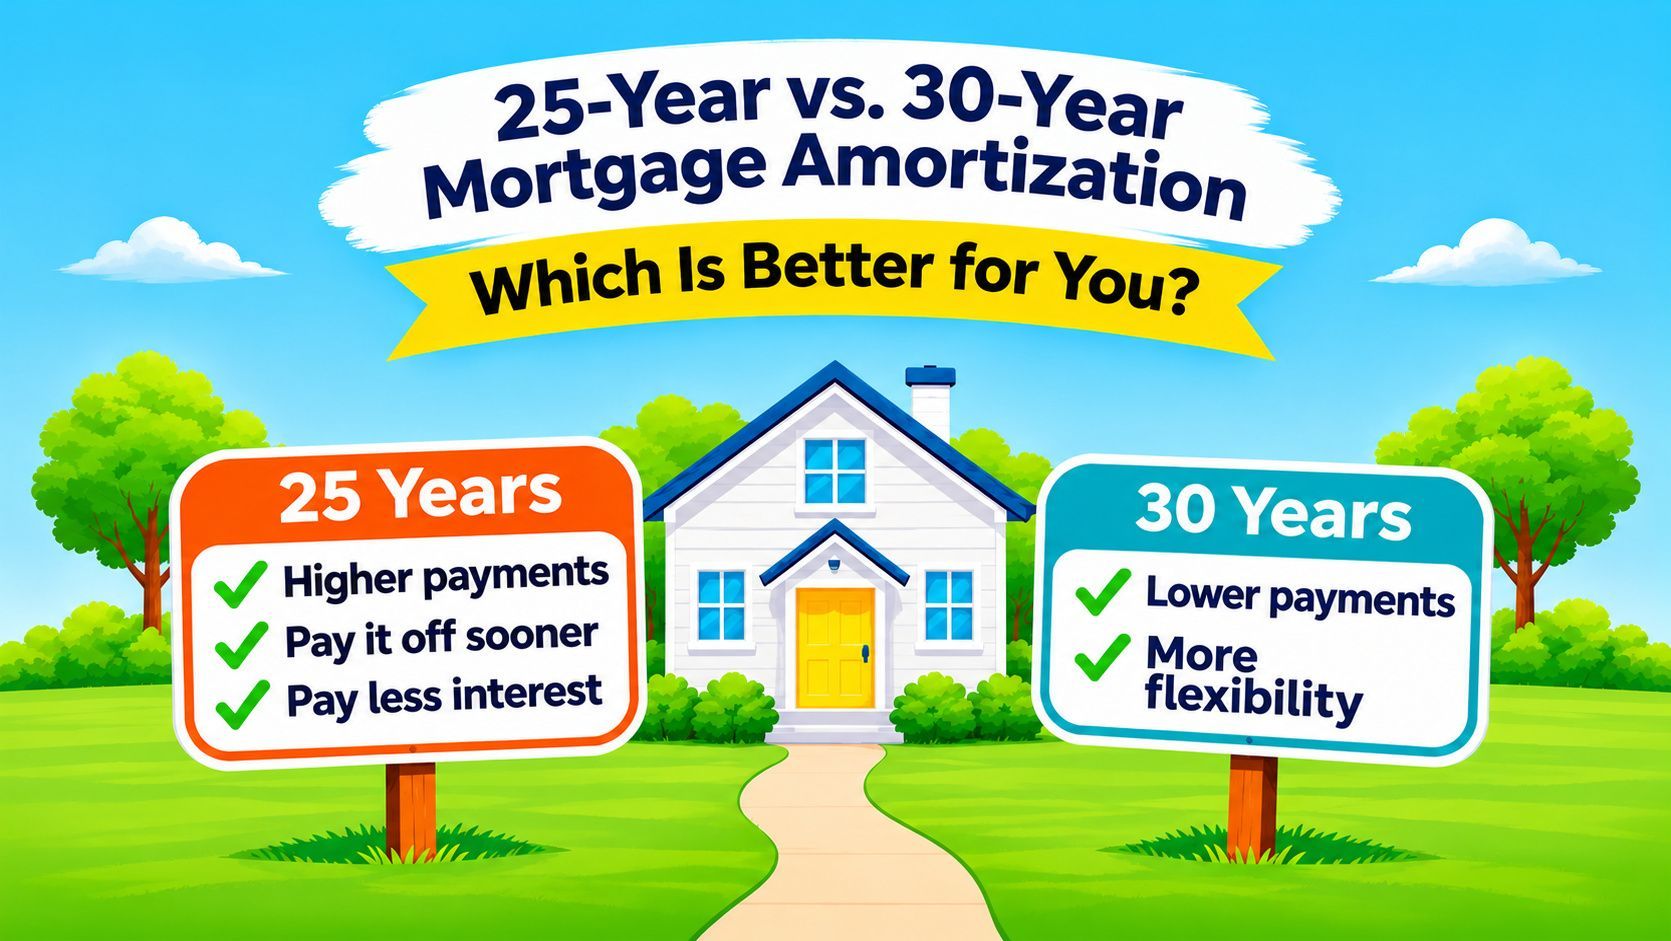
Graphic comparing 25-year vs. 30-year mortgage amortization with house and pros/cons lists
By Kelly Hudson • November 3, 2026
When it comes to mortgages, shorter isn't always better! You may have heard that a 25-year mortgage is better than a 30-year mortgage because you'll pay less interest. That's true, but there's more to consider! A shorter mortgage means higher monthly payments. A longer mortgage means lower payments, leaving more money for other things. So, which is better? It depends on your budget, lifestyle, and your future plans. What Is Mortgage Amortization? Amortization is the total time it would take to pay off your mortgage if you made all your regular payments. 25-year amortization: Higher payments, but you pay off your mortgage sooner and save on interest. 30-year amortization: Lower payments, but you take longer to pay off your mortgage and usually pay more interest. Let's Look at an Example: Imagine a $500,000 mortgage with a 4.5% interest rate.