Top 5 Questions to Ask your Mortgage Lender
KellyHudsonMortgages • December 19, 2016

The decision to purchase your first home can be a huge, life-changing event and you need to know exactly what you are getting into. Being prepared is the first step
When you are ready to buy a home, and you need mortgage there i s a lot of information to research and understand. I’ve put together a list of questions to help you make an educated decision regarding choosing the right mortgage lender for your situation
- How the penalties are calculated if I break my mortgage early? Specifically ask what rate the lender uses to calculate the “interest rate differential”.
- Typically, banks & credit unions have “posted rates” which are higher than their actual mortgage rates. They use these higher “posted rates” to calculate your penalty if you need to break your mortgage early.
- The inflated posted rate penalty can be 3- 5 times higher than a mortgage lender that does NOT inflate their posted rate.
- 60% of people break their mortgage before their term is over, so asking this question could save you thousands of dollars.
- Mortgage Penalties – Ouch… How Much??
- Is this a “collateral charge or revolving” mortgage or a conventional mortgage?
Many lenders have started putting all
of their mortgages into what is called a “collateral charge”. For the right client with a lot of equity in their home, this product can be very useful. Most big banks and credit unions only offer collateral charge mortgages.
- The disadvantage of a collateral charge mortgage is that you cannot “switch” it to another lender once your term is over at NO CHARGE.
- You have to pay discharge a collateral charge mortgage and re-register a new mortgage with your new lender, which will cost you an around $1000 for legal fees and appraisal costs. It will cost you to leave your current lender… which makes these mortgages sticky and hard to get out of.
- Collateral vs Conventional Mortgages… What the Banks don’t want you to know…
- Can I “blend and extend” my mortgage if I buy another home?
- Most variable rate mortgages cannot be “blended”. Typically, the penalty to break a variable is 3 months’ interest. Some lenders have quietly changed their policies and now instead of allowing you to add new money to a mortgage in the event of a new purchase, they require you to break your mortgage and pay the full penalty.
- Some clients have been caught off guard by sneaky lenders who don’t tell them this until only a few days before close, at which time it’s too late to switch lenders.
- What happens to my mortgage life and/or disability insurance if I switch to a new lender at the end of my term?
- For people who take out Mortgage insurance offered by their bank or lender, the challenge is that if you want to “switch” your mortgage to another lender at the end of your term, you have to re-apply for insurance.
- The downside to this is that you’ll be five years older (more expensive), and if you have developed any health issues during the previous 5 years, you may not be able to requalify for Mortgage insurance.
- Purchasing mortgage insurance, separate from your lender, stays in place the whole time you have your mortgage, it doesn’t matter who your lender is.
- What happens at the completion of your mortgage term (typically 5 years)?
- Most banks know that clients won’t negotiate the best rates so typically their renewal offer isn’t competitive.
- Working with an independent mortgage expert keeps lenders honest about rates. An independent mortgage expert will make sure you have the best options available every time your mortgage comes due.
Would you like more information regarding mortgages? Give me a call and let’s have a chat.
Kelly Hudson
Mortgage Expert
Mobile: 604-312-5009
Kelly@KellyHudsonMortgages.com
www.KellyHudsonMortgages.com
Kelly Hudson
MORTGAGE ARCHITECTS
RECENT POSTS
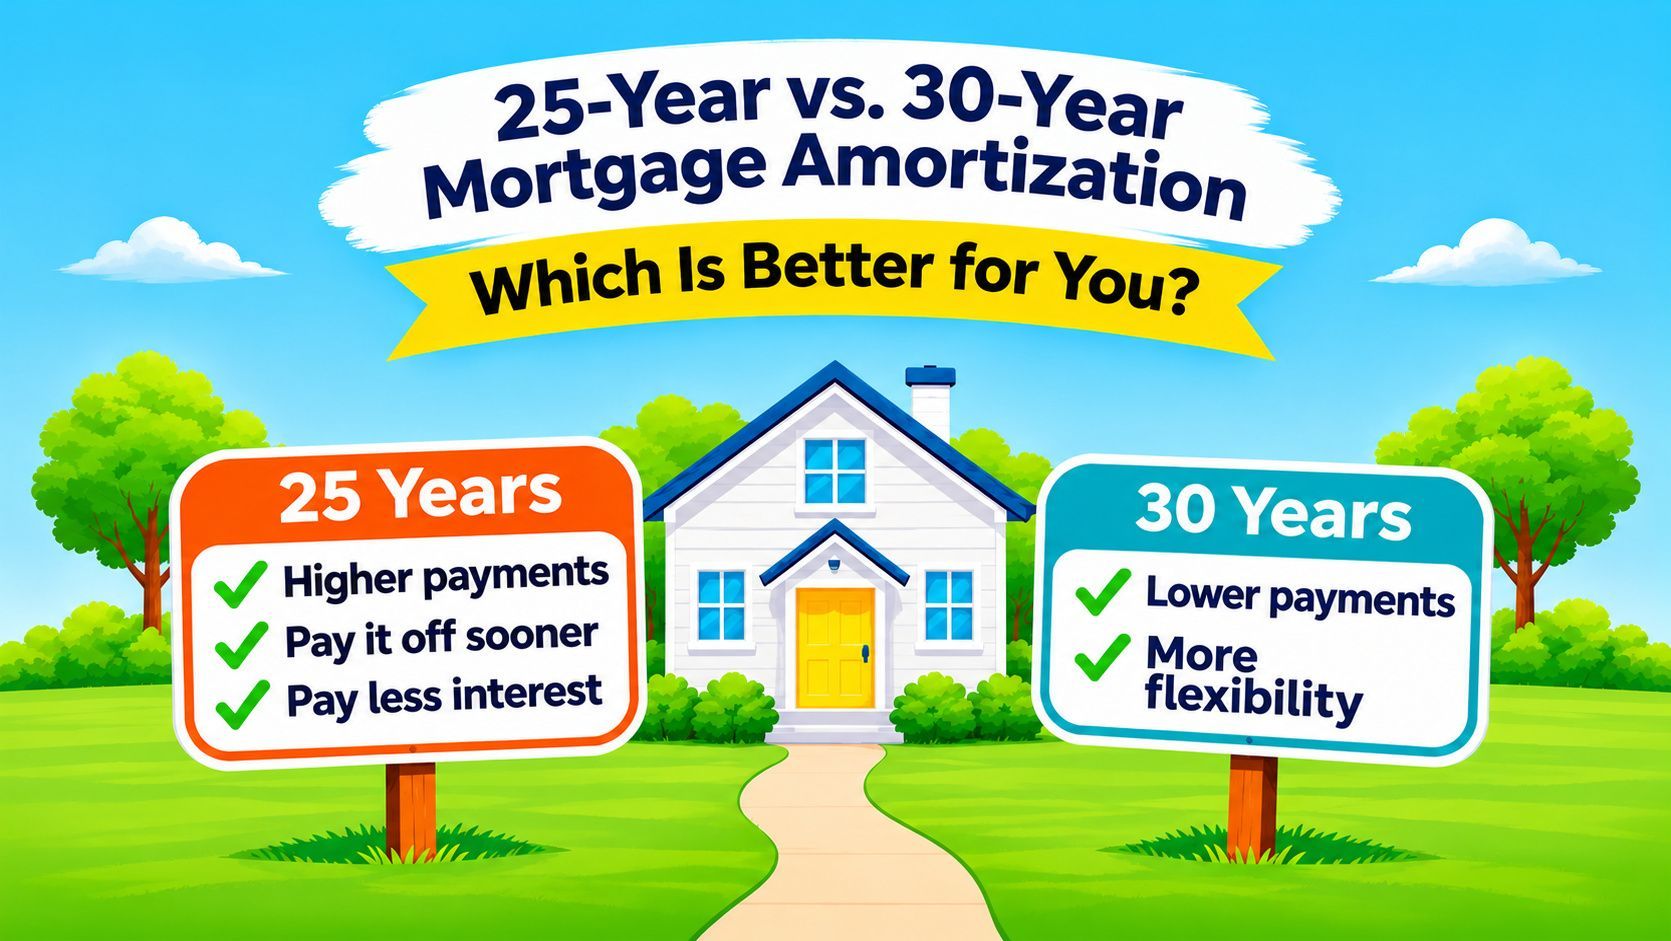
When it comes to mortgages, shorter isn't always better! You may have heard that a 25-year mortgage is better than a 30-year mortgage because you'll pay less interest. That's true, but there's more to consider! A shorter mortgage means higher monthly payments. A longer mortgage means lower payments, leaving more money for other things. So, which is better? It depends on your budget, lifestyle, and your future plans. What Is Mortgage Amortization? Amortization is the total time it would take to pay off your mortgage if you made all your regular payments. 25-year amortization: Higher payments, but you pay off your mortgage sooner and save on interest. 30-year amortization: Lower payments, but you take longer to pay off your mortgage and usually pay more interest. Let's Look at an Example: Imagine a $500,000 mortgage with a 4.5% interest rate.
For many Canadians, their home is their biggest financial asset. After years of homeownership, they may have paid off most (or all) or all their mortgage and built a lot of equity in their home. The problem: You can own a valuable home and still struggle to pay your monthly bills. You've probably heard the phrase “house rich and cash poor.” This is exactly what it means. For Canadian homeowners aged 55 and older, a reverse mortgage is one option worth looking at. It's definitely NOT the right solution for everyone. But for some homeowners, it can provide extra cash while allowing them to stay in the home they love. What Is a Reverse Mortgage? A reverse mortgage allows homeowners 55+ to access some of the equity in their home without selling it. Unlike a regular mortgage, you don't normally have to make monthly mortgage payments. Instead, interest is added to the amount you borrowed, so the balance grows over time. The mortgage is typically repaid when the home is sold, the homeowners permanently move out, or the last homeowner dies. And one of the biggest misconceptions I hear? The bank does NOT own your home. You do. You stay on title and continue to own your home. The money you receive is also generally tax-free because you're borrowing the money - it's not income. What Does “House Rich, Cash Poor” Look Like? Let's say you've lived in your home for 30 years. Your mortgage is paid off and your home is now worth $1 million. Sounds pretty good, right? But your retirement income may come from CPP, OAS, a pension and your savings. At the same time, groceries, property taxes, insurance, utilities and everything else seem to keep getting more expensive. So, while you may have hundreds of thousands of dollars in home equity, your monthly budget can still feel tight. You have the money. It's just tied up in your house. A reverse mortgage is one way to access some of that equity without having to sell and move. What Could You Use the Money For? There are generally no restrictions on how you use the money. Everyone's situation is different, but I've seen homeowners consider a reverse mortgage to: Pay off an existing mortgage, credit cards or other debts Add to your monthly retirement income Make home repairs or accessibility upgrades so you can stay in your home longer Pay for in-home care Help children or grandchildren financially Cover unexpected expenses or create an emergency fund Depending on the product, you may also have choices about how and when you receive the money. You don't necessarily have to take everything at once. Why Not Just Sell and Downsize? This is usually one of the first alternatives we talk about. Downsizing can make perfect sense—but it's not always as easy or as inexpensive as people think. A smaller home or condo can still be expensive, especially in many BC communities. Then add real estate commissions, legal fees, moving expenses, strata fees and other costs. And there's another part of this decision that has nothing to do with numbers. Your home is more than an asset on a balance sheet. Maybe you've lived there for 30 years. Your friends are nearby. You know your neighbours. Your doctor, family and community are close. Maybe you simply love your home and don't want to move. For many retirees, being able to stay in their home is an important part of their retirement plan. So... What's the Catch? There isn't any free money here. Reverse mortgage rates are typically higher than traditional mortgage rates. And because you aren't making regular mortgage payments, the interest gets added to the amount you borrowed. That means the amount you owe grows over time and the equity left in your home can decrease. There can also be appraisal, legal, setup and closing costs. Depending on the mortgage and when you repay it, there may also be a penalty. And remember—you still own the house. That means you're still responsible for maintaining it, keeping it insured and paying the property taxes. That's why it's important to look beyond the interest rate and understand the long-term costs. What About My Children's Inheritance? This is a conversation worth having with your family. A reverse mortgage will normally mean there is less equity left in your home for your estate. For some homeowners, leaving as much as possible to their children is extremely important. Others look at it differently. They would rather use some of the equity they've spent decades building to make their own retirement more comfortable. And some parents decide they'd rather help their children or grandchildren now , while they're still here to see them enjoy it (i.e. a gifted down payment). There's no right or wrong answer. It's your home, your equity and your decision. Reverse Mortgage or Home Equity Line of Credit (HELOC) ? A HELOC is another way to access the equity in your home. But there's an important difference. With a HELOC, you need enough income to qualify, and you'll need to make monthly payments. That can be difficult for someone who is retired and has a valuable home but limited monthly income. A reverse mortgage works differently because it's designed for older homeowners. One option isn't automatically better than the other. Maybe a HELOC makes more sense. Maybe refinancing makes more sense. Maybe a reverse mortgage does. It depends on your income, age, equity, monthly cash flow and, most importantly, what you're trying to accomplish. Is a Reverse Mortgage Right for You?