Collateral Charge vs. Standard Charge Mortgages in Canada

Kelly Hudson • October 15, 2025

When you’re buying a home in Canada, you’ll hear a lot of new terms. One of those is how your mortgage is registered: as a standard charge or a collateral charge.


This choice matters because it affects your flexibility, your costs if you ever switch lenders, and how easy it is to borrow more money later. Let’s break it down in simple terms.


What’s the Big Difference?

Both types of mortgages let you borrow money to buy your home. The difference comes in how the lender registers the loan against your property.
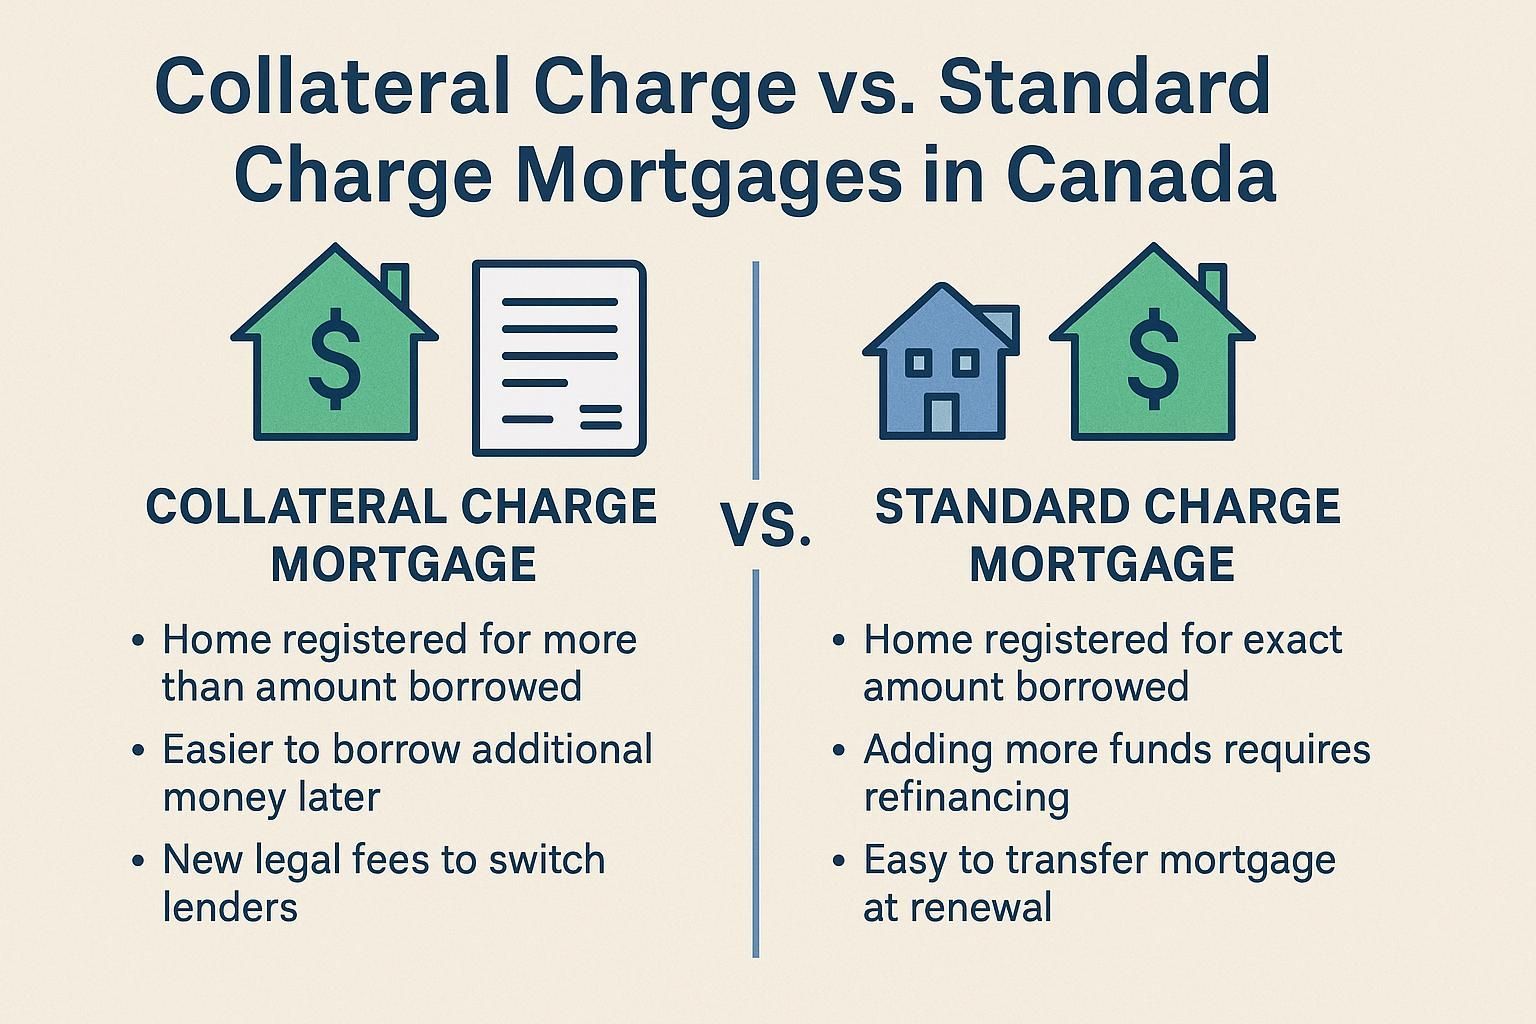
  • Standard Charge Mortgage
    This is the traditional way most lenders register mortgages. The charge is for the exact amount you borrow. For example, if your mortgage is $400,000, the charge is for $400,000.
  • Collateral Charge Mortgage
    This type registers your home for
    more than the amount you actually borrow—sometimes up to 100% or even 125% of your home’s value. So, if you borrow $400,000 on a $500,000 home, the lender might register it as $625,000.


Why? Because it makes it easier to borrow more later—without hiring a lawyer again or paying extra legal fees.


Advantages of Collateral Charge Mortgages


  1. Easy Access to Equity
    If your home goes up in value or you want to use equity for renovations, debt consolidation, or investments, you can often access those funds directly with your lender.
  2. You need the income to qualify for the larger mortgage
  3. No New Legal Fees
    Since the mortgage is already registered for a larger amount, you don’t have to pay a lawyer if you want to increase your mortgage with the same lender.
  4. Good for HELOCs
    Home Equity Lines of Credit (HELOCs) are always registered as collateral charges. They’re designed for people who want ongoing access to their home equity.

Downsides of Collateral Charge Mortgages


  1. Harder to Switch Lenders
    If you want to change lenders at renewal to get a better rate or different features, you can’t just “transfer” your mortgage for free. With a collateral charge, most lenders require you to start fresh, which means paying new legal fees—anywhere from $1,000 or more.
  2. Negotiating Power is Limited
    Since switching to a new lender will cost more, you may lose some leverage when asking your current lender for a better deal.
  3. Second Mortgages Can Be Tricky
    Because the collateral charge takes up more of your home’s value, it may block other lenders from giving you a second mortgage—unless your home value has increased a lot.

Advantages of Standard Charge Mortgages


  1. Easy to Switch Lenders
    At renewal, you can shop around and transfer to another lender with little or no cost. This helps keep your options open and gives you stronger negotiating power.
  2. Simple and Clear
    Your mortgage is registered for exactly what you borrow. If you need more money later, you can add a second mortgage or line of credit.
  3. Fewer Surprises
    Because the registered amount matches what you owe, you know exactly where you stand.

Downsides of Standard Charge Mortgages


  1. Extra Legal Fees if You Refinance
    If you want to borrow more money later (say for renovations), you’ll usually need to hire a lawyer and pay legal fees.
  2. Less Built-In Flexibility
    Unlike collateral charges, standard charges don’t give you instant access to more equity without extra steps.

What’s Changed in the last 10 years?


Back in 2014, TD and ING (now Tangerine) had already switched to collateral charges for all new mortgages. Today, most major banks in Canada still use collateral charges for HELOCs and some mortgage products. Some lenders continue to offer standard charge mortgages, especially credit unions and non-bank lenders.

The key difference now is that more borrowers are aware of the trade-offs. With rising home prices and tighter mortgage rules (like the stress test), being strategic about how your mortgage is registered matters more than ever.
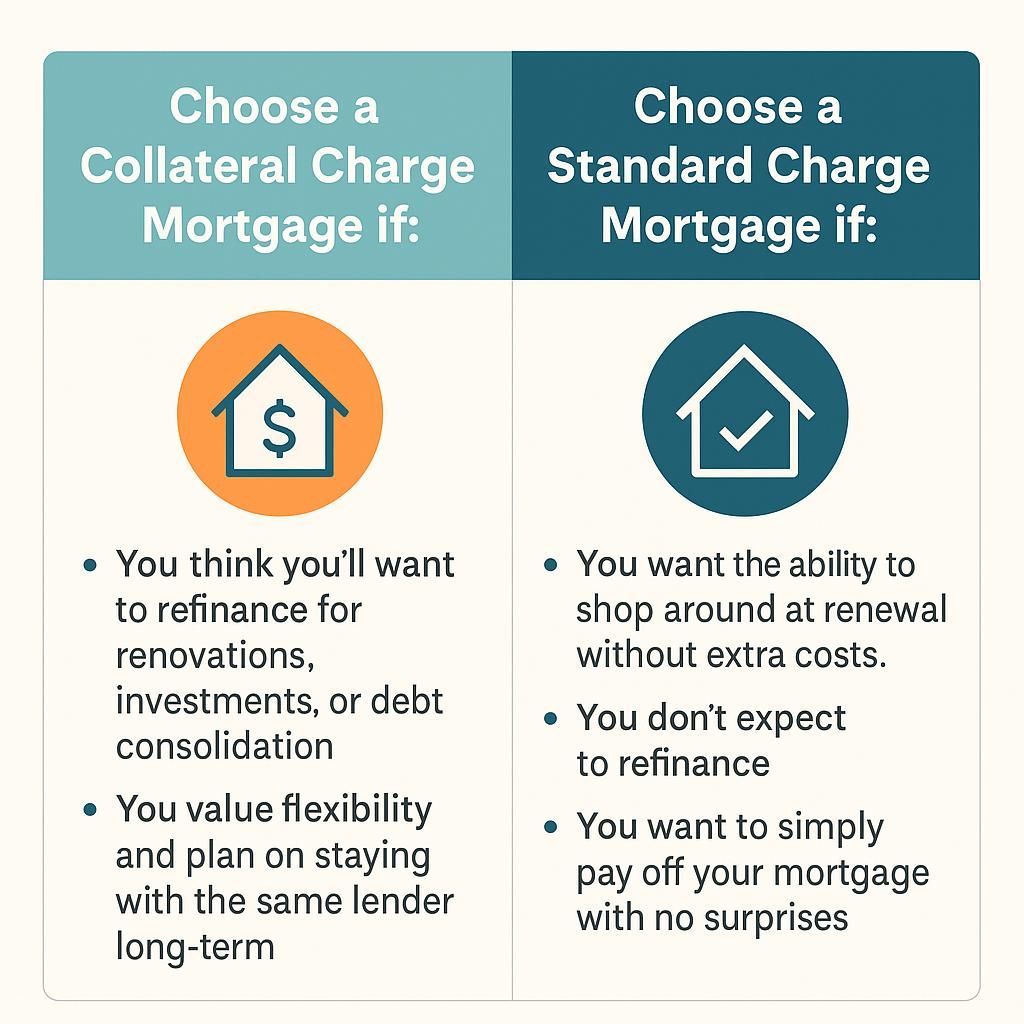

Which One Is Right for You?


  • Choose a Collateral Charge Mortgage if:
  • You think you’ll want to refinance for renovations, investments, or debt consolidation.
  • You value flexibility plan on staying with the same lender long-term.
  • Choose a Standard Charge Mortgage if:
  • You want the ability to shop around at renewal without extra costs.
  • You don’t expect to refinance.
  • You want to simply pay off your mortgage with no surprises.

Final Word: Talk to a Mortgage Broker

Every homeowner’s situation is different. Choosing between a standard or collateral charge mortgage adds one more decision to an already big process.


That’s where a mortgage broker can help. Brokers work with many different lenders, explain the pros and cons, and guide you to the option that fits your goals. Whether you value flexibility, lower fees, or freedom to shop around, getting expert advice makes the choice much easier.


Bottom Line: A collateral charge mortgage gives you flexibility to borrow more later but limits your ability to switch lenders cheaply. A standard charge mortgage makes it easier to shop around but may cost more if you need to refinance. The right choice depends on your long-term plans—and that’s why expert advice from your mortgage broker is key.


Are you considering buying a home? As you can tell there is lots to discuss, let’s have a chat and find a mortgage that works for you and not the bank.


Kelly Hudson
Mortgage Expert
Mortgage Architects – A Better Way
Mobile: 604-312-5009

Kelly@KellyHudsonMortgages.com

www.KellyHudsonMortgages.com

Kelly Hudson
MORTGAGE ARCHITECTS
RECENT POSTS 

Reverse mortgage ad with smiling couple, house, flowers, and question marks about using home equity
By Kelly Hudson • October 9, 2026
For many Canadians, their home is their biggest financial asset. After years of homeownership, they may have paid off most (or all) or all their mortgage and built a lot of equity in their home. The problem: You can own a valuable home and still struggle to pay your monthly bills. You've probably heard the phrase “house rich and cash poor.” This is exactly what it means. For Canadian homeowners aged 55 and older, a reverse mortgage is one option worth looking at. It's definitely NOT the right solution for everyone. But for some homeowners, it can provide extra cash while allowing them to stay in the home they love. What Is a Reverse Mortgage? A reverse mortgage allows homeowners 55+ to access some of the equity in their home without selling it. Unlike a regular mortgage, you don't normally have to make monthly mortgage payments. Instead, interest is added to the amount you borrowed, so the balance grows over time. The mortgage is typically repaid when the home is sold, the homeowners permanently move out, or the last homeowner dies. And one of the biggest misconceptions I hear? The bank does NOT own your home. You do. You stay on title and continue to own your home. The money you receive is also generally tax-free because you're borrowing the money - it's not income. What Does “House Rich, Cash Poor” Look Like? Let's say you've lived in your home for 30 years. Your mortgage is paid off and your home is now worth $1 million. Sounds pretty good, right? But your retirement income may come from CPP, OAS, a pension and your savings. At the same time, groceries, property taxes, insurance, utilities and everything else seem to keep getting more expensive. So, while you may have hundreds of thousands of dollars in home equity, your monthly budget can still feel tight. You have the money. It's just tied up in your house. A reverse mortgage is one way to access some of that equity without having to sell and move. What Could You Use the Money For? There are generally no restrictions on how you use the money. Everyone's situation is different, but I've seen homeowners consider a reverse mortgage to: Pay off an existing mortgage, credit cards or other debts Add to your monthly retirement income Make home repairs or accessibility upgrades so you can stay in your home longer Pay for in-home care Help children or grandchildren financially Cover unexpected expenses or create an emergency fund Depending on the product, you may also have choices about how and when you receive the money. You don't necessarily have to take everything at once. Why Not Just Sell and Downsize? This is usually one of the first alternatives we talk about. Downsizing can make perfect sense—but it's not always as easy or as inexpensive as people think. A smaller home or condo can still be expensive, especially in many BC communities. Then add real estate commissions, legal fees, moving expenses, strata fees and other costs. And there's another part of this decision that has nothing to do with numbers. Your home is more than an asset on a balance sheet. Maybe you've lived there for 30 years. Your friends are nearby. You know your neighbours. Your doctor, family and community are close. Maybe you simply love your home and don't want to move. For many retirees, being able to stay in their home is an important part of their retirement plan. So... What's the Catch? There isn't any free money here. Reverse mortgage rates are typically higher than traditional mortgage rates. And because you aren't making regular mortgage payments, the interest gets added to the amount you borrowed. That means the amount you owe grows over time and the equity left in your home can decrease. There can also be appraisal, legal, setup and closing costs. Depending on the mortgage and when you repay it, there may also be a penalty. And remember—you still own the house. That means you're still responsible for maintaining it, keeping it insured and paying the property taxes. That's why it's important to look beyond the interest rate and understand the long-term costs. What About My Children's Inheritance? This is a conversation worth having with your family. A reverse mortgage will normally mean there is less equity left in your home for your estate. For some homeowners, leaving as much as possible to their children is extremely important. Others look at it differently. They would rather use some of the equity they've spent decades building to make their own retirement more comfortable. And some parents decide they'd rather help their children or grandchildren now , while they're still here to see them enjoy it (i.e. a gifted down payment). There's no right or wrong answer. It's your home, your equity and your decision. Reverse Mortgage or Home Equity Line of Credit (HELOC) ? A HELOC is another way to access the equity in your home. But there's an important difference. With a HELOC, you need enough income to qualify, and you'll need to make monthly payments. That can be difficult for someone who is retired and has a valuable home but limited monthly income. A reverse mortgage works differently because it's designed for older homeowners. One option isn't automatically better than the other. Maybe a HELOC makes more sense. Maybe refinancing makes more sense. Maybe a reverse mortgage does. It depends on your income, age, equity, monthly cash flow and, most importantly, what you're trying to accomplish. Is a Reverse Mortgage Right for You? 
Infographic on Canadian mortgage lending ratios, with house icons, GDS, TDS, and “How Much Mortgage Can You Afford?” text
By Kelly Hudson • September 16, 2026
If you're thinking about buying a home in BC, one of the first questions you probably have is: How much mortgage can I qualify for? Your income is certainly important, but it isn't the only number a mortgage lender looks at. Lenders also consider your debts, credit history, down payment, property costs and something called your mortgage lending ratios . The two ratios you'll hear about most often are GDS (Gross Debt Service) and TDS (Total Debt Service) . The names sound complicated. The math really isn't. Understanding how GDS and TDS work can give you a much better idea of what you may qualify for — and why two people earning the same income could qualify for very different mortgage amounts.