How to Pick the Best Mortgage for YOUR Situation!
Most Canadians are conditioned to think that the lowest interest rate means the best mortgage product. Although sometimes that is true, a mortgage is much more than just an interest rate. You can save yourself a lot of money if you pay attention to the fine print for the total cost of your mortgage.
To pick the best mortgage, you need to understand how mortgages work and what your options are. This comes with Mortgage Intelligence (my specialty)!
Once you’ve selected the type of mortgage, then you’ll need to work with your Mortgage Broker (me!) to find the best fit for you and your situation.
- Are you planning to move in the next 5 years (Upsize? Downsize?)
- Will your family be growing/shrinking?
- Will your employment change and if it does will you need to relocate?
- Would $1000’s in penalties impact you if you need to break your mortgage?
- What types of debts do you have? Credit cards? Car loan? Student loan? Line of Credit?
Why do all this work? Because it will have a direct impact on your bottom line. A mortgage is made up of two parts—the principal and interest—you need to pay attention to how and when these parts get paid down.
- Ideally, you want to minimize your interest payments and maximize the principal payments.
To pick the best formula for your situation, you’ll first need to understand some of the factors that impact how much interest you’ll pay for your mortgage loan.
Here are 6 mortgage terms to help you make the best decision for your situation.
Amortization
Amortization is a
fancy word that means the “life of your mortgage” OR how long it takes to pay off your mortgage if you paid your mortgage for “X” years. The amount of your mortgage loan repayment is calculated based on the length of time you agree to paying off that debt. In Canada, the standard amortization period is 25 years.
- If you have a 20% down payment (or higher) you could amortize over 30-years
- BLOG 5 GREAT Reasons To Provide a 20% Down Payment when Buying a Home
Picking the best mortgage is not just about qualifying for the mortgage. The amortization period is integral in the best mortgage decision because it will decide how much or how little interest you will pay during the life of the mortgage loan.
- The longer the amortization period (25 years vs 30 years) the more interest you will pay.
- Therefore, a shorter amortization period will lower your overall cost of borrowing BUT you must be able to afford/qualify for the higher payments.
Once you’ve decided on your amortization, you will need to decide how frequently you would like to make your mortgage payments. Every mortgage payment (consisting of both interest and principal) will help reduce your principal (the amount of money you borrowed) and eventually reduces the overall interest you pay on this loan.
- Monthly, bi-monthly, accelerated bi-weekly or weekly mortgage payments.
- BLOG Mortgage Payment Frequency - Accelerated Bi-Weekly vs Bi-Weekly Payments
Term
In the 1980’s mortgage interest rates were as high as 22%. Interest rates can change over time therefore, lenders don’t want to negotiate a 25-year loan at 5% interest if the interest rates go up to 10% in 5 years. To avoid the risk, lenders break your mortgage amortization into smaller terms.
- The term is shorter than the amortization period and locks you into your pre-negotiated rates during that time.
- The length of term you choose (most Canadians choose 5 years) will depend partly on if you think interest rates will rise or fall. Typical terms are: 1, 2, 3, 4, 5, 7 & 10.
About 3-6 months before your current term matures, your current lender usually sends you a renewal notice with options on rates for the various terms they offer.
- Once your mortgage matures - you can stay with your current lender or move to a new lender.
Once you get your renewal notice, you need to contact your mortgage broker (me!) to ensure you’re choosing the best option for your situation.
Closed Mortgage
A closed mortgage usually offers the lowest interest rates.
Closed mortgages cannot be paid off before the end of its term without triggering a penalty. Some lenders allow for a
partial prepayment of a closed mortgage by increasing the mortgage payment or a lump sum prepayment.
- If you try and “break your mortgage” or if any prepayments are made above the stipulated allowance the lender allows, a penalty will be charged.
- BLOG Mortgage Penalties – Ouch… How Much??
Open Mortgage
An open mortgage is a more flexible mortgage that allows you to pay off your mortgage in part or in full before the end of its term without penalty. Because of the flexibility the interest rates are higher.
- The interest rates for an open mortgage are typically 3-4% higher than a closed rate mortgage.
- i.e., a home buyer may pay 7.99% for a 5-year open mortgage vs. 4.99% for a five-year closed mortgage.
If you plan to sell your home soon or expect a large sum of money, an open mortgage can be a great option. Most lenders will allow you to convert from an open to a closed mortgage at any time (and switch you to lower rates).
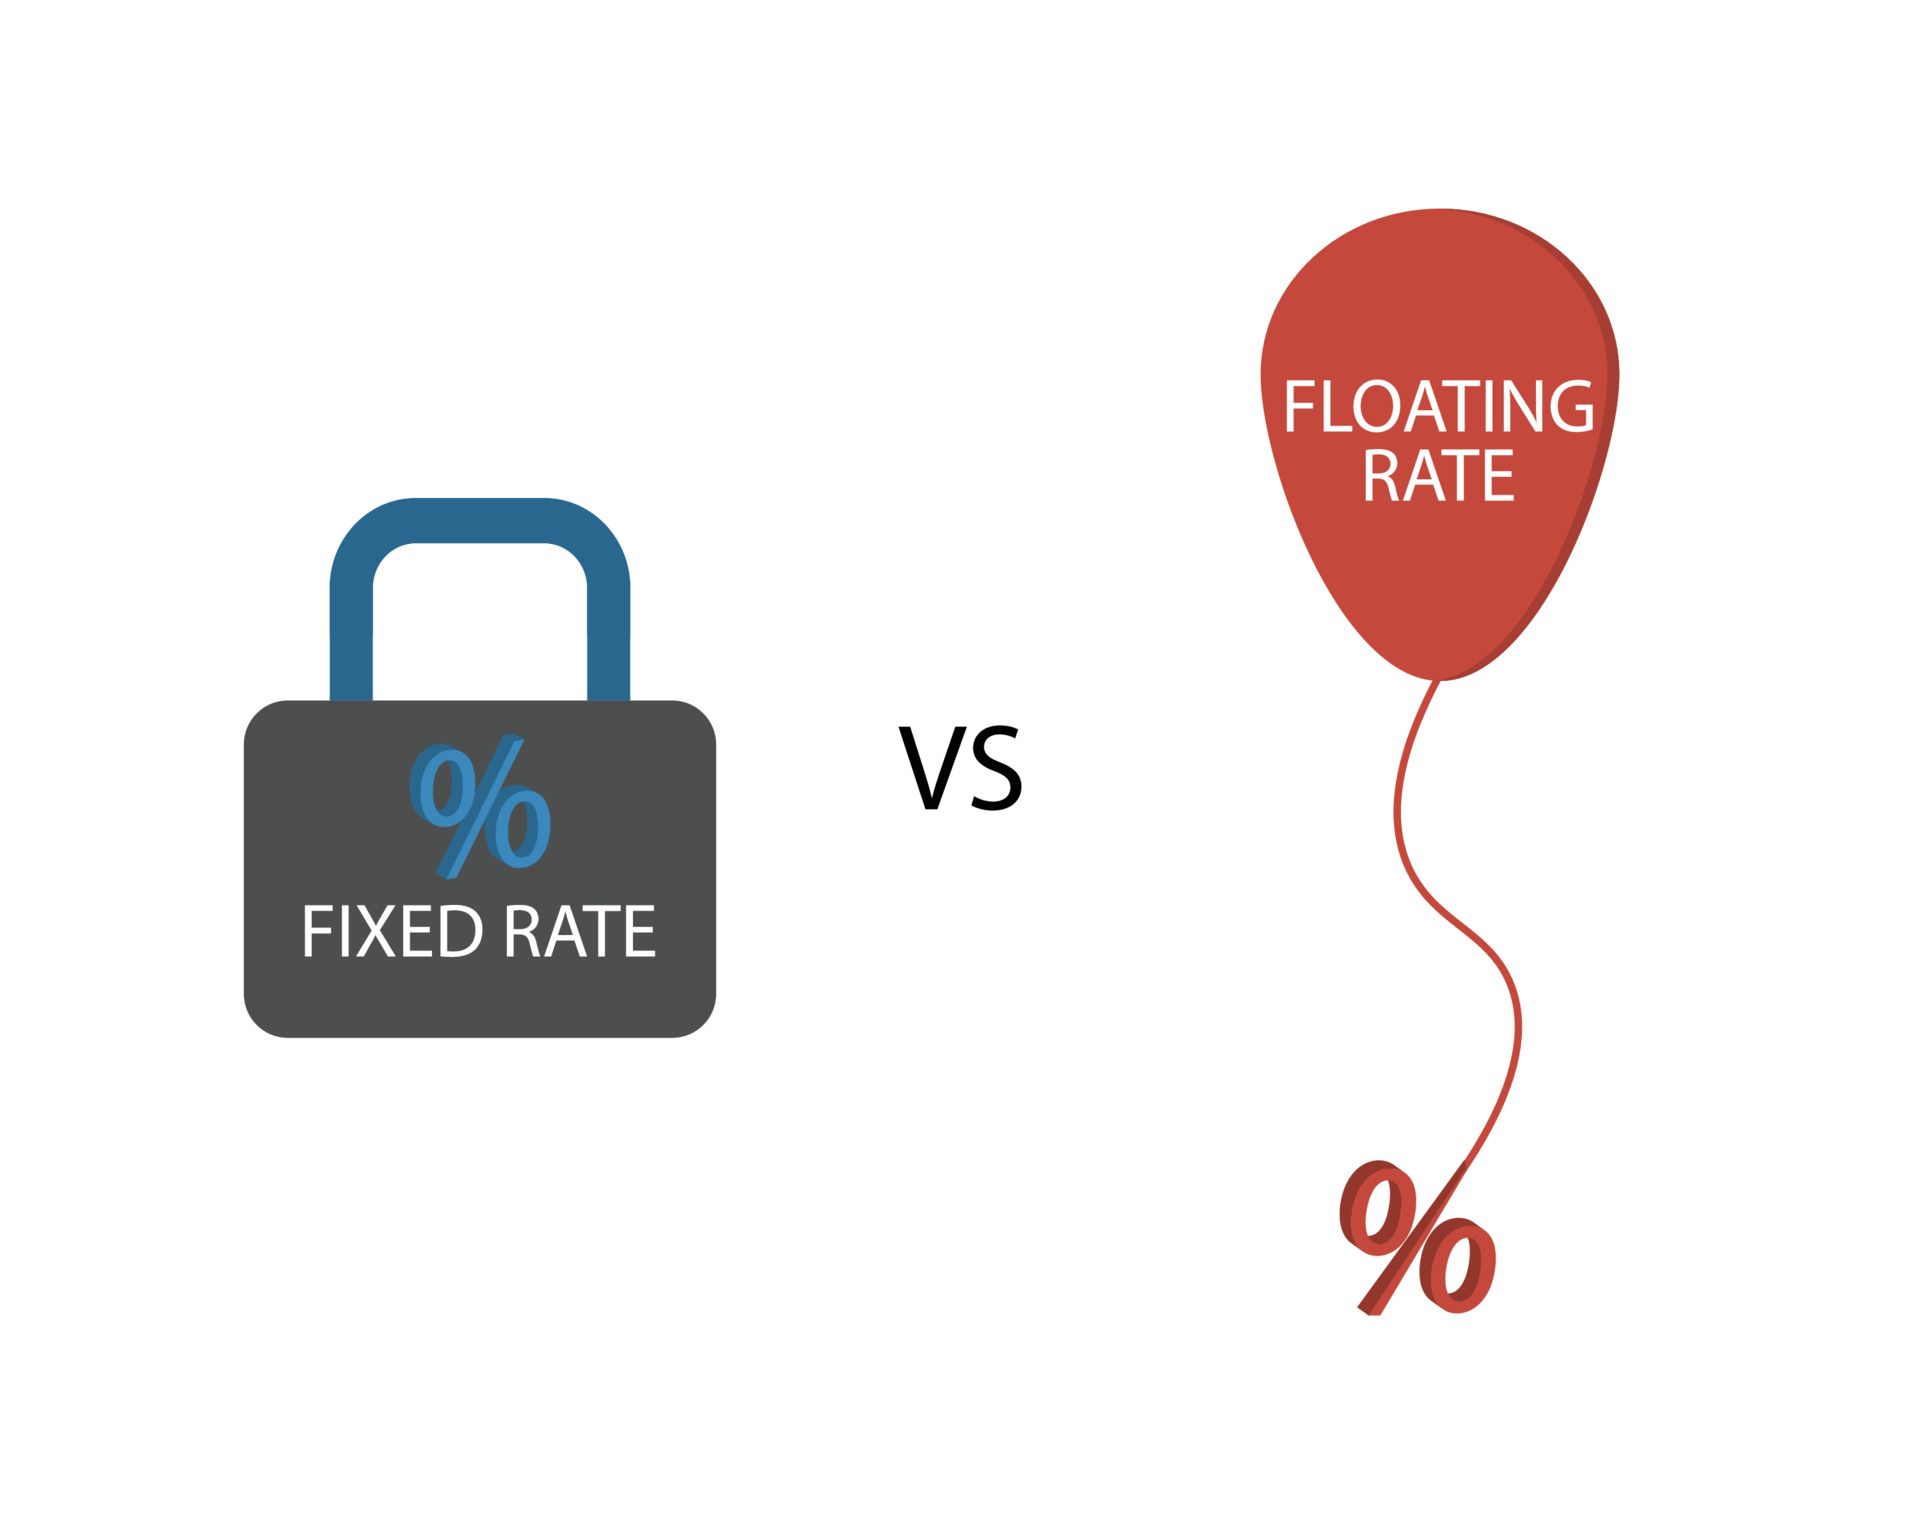
Fixed mortgage – you have the same payment for the term of the mortgage
Variable mortgage (Floating rate)
– the mortgage rate (and your mortgage payment) varies depending on the Bank of Canada rate (Prime)
Fixed vs. Variable Pros & Cons (in a nutshell) for more information check out my BLOG
Fixed vs. Variable Rate Mortgages – Pros & Cons
Fixed rate:
- Pro – you would have the same mortgage payment for the entire term of the mortgage
- Your mortgage payments are not affected by Bank of Canada Rate
- Think of fixed rate as an insurance policy – you may pay a premium to guarantee “fixed” rates for the balance of the term
- Pro – can port a fixed mortgage (*MUST requalify)
- Con – Typically fixed rates are higher than variable interest rates
- Con – MUCH higher penalties if you need to break your mortgage (can be 4-5% of outstanding balance with Banks/Credit Unions)
- 60% of home owners, break their mortgage before it matures! There are penalties to break your mortgage, click on this GREAT 3 minute video from the Globe & Mail explaining how Banks calculate mortgage penalties for both Variable & Fixed mortgages and how banks squeeze even more money out of their clients by giving discounts off their inflated posted rates Drawing Conclusions: How much does it cost to break a mortgage?
- BLOG 9 Reasons Why People Break Their Mortgages
Variable rate:
- Pro – typically variable rates are lower than the fixed rates
- Pro – Penalty for breaking is 3 months interest.
- Pro – you can lock into a fixed rate mortgage (assuming your mortgage is in good standing) at any time, based on the amount of time remaining on your mortgage and the current posted rates.
- i.e. If you have a 5-year variable mortgage and you want to move to Fixed after 2 years, you would lock into the current 3 year fixed posted rate
- Con – May or may not be able to port a variable mortgage – will depend on the lender (*MUST requalify)
- Con – Mortgage payments will increase/decrease based on the Bank of Canada rate – Dec. 2023 at 5.00% and the lenders prime rate = Prime 7.20%
- Bank of Canada meets 8 times a year
- Every 0.25% increase with the lender Prime rate will cost you an extra $13/$100,000 borrowed. i.e., $300K mortgage an increase of 0.25% will cost you about $39/month more.
BLOG
10 Helpful Words to Know when Buying a Home
The best way to decide on the best mortgage is to contact your
friendly neighbourhood mortgage broker. Mortgages are complicated, but they don't have to be... Engage an expert!
Give me a call and let’s discuss a mortgage that works for you (not the bank)!
Kelly Hudson
Mortgage Expert
Mortgage Architects – A Better Way
Mobile 604-312-5009
Kelly@KellyHudsonMortgages.com
www.KellyHudsonMortgages.com