What is the difference between a Mortgage Broker & a Mortgage Specialist (hint – specialists work for the bank)!!
Kelly Hudson • July 13, 2018
With the importance of real estate in Canada, it is vital to understand how the various professionals in the sector operate when buying a home.
Sooooooo… what is the difference between a Mortgage Specialist & a Mortgage Broker?
On the surface they sound the same
- They both arrange mortgages
- They both can offer advice and help you select a mortgage, right?
WRONG!!! There are many differences… Let’s check some of them out!
- A Mortgage Broker works for you!
Their role is to act as a link between you and the lenders so that you do not have to spend your valuable time learning about mortgages and shopping around for the perfect mortgage. Mortgage brokers do the legwork and negotiate on your behalf for lenders. They are your point of contact for everything related to your financing your home.
- Bank specialists are employed and paid by the bank and work on the bank’s behalf.
- A Mortgage Broker can work with many different lenders
across Canada, rather than working for one financial institution. Therefore, Mortgage Brokers can offer you more choices with competitive rates and terms including: Big banks, Credit Unions, Trust Companies, Monoline Lenders (broker only banks), private lenders.
- Usually Mortgage Specialists only have access to their lender’s products. In a typical situation, homeowners could end up with a higher interest rate than other institutions. This occurs because the homeowner must negotiate for themselves and Mortgage Specialists are usually paid according to the rate they sell you.
- A Broker must successfully complete a Provincially regulated Mortgage Broker course and exam.
(
In BC, Mortgage Brokers must be licensed by
FICOM
) They continue to maintain their good status to keep that license by taking professional development education courses
- Bank specialists are not licensed and require no formal training. There are no standards for educational requirements (although most Lenders do provide some in-house training).
- Because Mortgage Brokers don’t work for a specific lender, you get impartial advice
about a variety of lenders
- A bank specialist can only offer their own institutions products, good or bad.
- Specialists don’t have access to other lenders, so they won’t recommend another lender’s product offerings.
- Mortgage Brokers use their knowledge and experience to negotiate the best possible terms and rates for you from a variety of lenders, based on the best fit for your situation.
- When you see a bank specialist, the mortgage negotiating is typically left up to you.
- Will the bank specialist negotiate on your behalf or the banks?
- For conventional financing, the services of a mortgager broker are generally FREE to you
. If there is a cost, you will be advised of those costs up front.
Brokers get a finder’s fee from the lender once they place your mortgage. Therefore, brokers are motivated to get the best terms and rates for their clients.
- Bank specialists are paid by the bank
- Some banks offer bonuses if specialist gets their client to pay higher interest rates or sign up for other bank services.
- Mortgage Broker’s work on a referral basis and are self employed. Most of their business is done through word of mouth referrals, therefore a Mortgage Broker is motivated to ensure their clients are extremely happy and satisfied to keep their business growing.
- A bank specialist is generally an employee of the bank, generating business through the bank’s existing customers.
-
- Most Mortgage Brokers are available for appointments outside banking hours (nights, weekends) at their client’s convenience.
- Bank specialists are generally only available during regular banking hours.
- Most Mortgage Brokers are available for appointments outside banking hours (nights, weekends) at their client’s convenience.
- Mortgage Brokers are focused on your mortgage
-
- Specialists are trained and rewarded on cross selling. Some will push you to consolidate all your banking services with them when getting a mortgage (credit cards, insurance, RRSP, lines of credit, etc.)
-
 Would you ask Tim Hortons who makes the best coffee and expect them to say Starbucks? Not likely… So why would you ask a Mortgage Specialist who works for a bank, to tell you which Lender has the best mortgage product for your situation?
For additional information check out my BLOG Top 10 Reasons to Use an Independent Mortgage Broker
Mortgages are confusing… Give me a call and let’s discuss a mortgage that works for you (not the bank)!
Kelly Hudson
MORTGAGE ARCHITECTS
RECENT POSTS
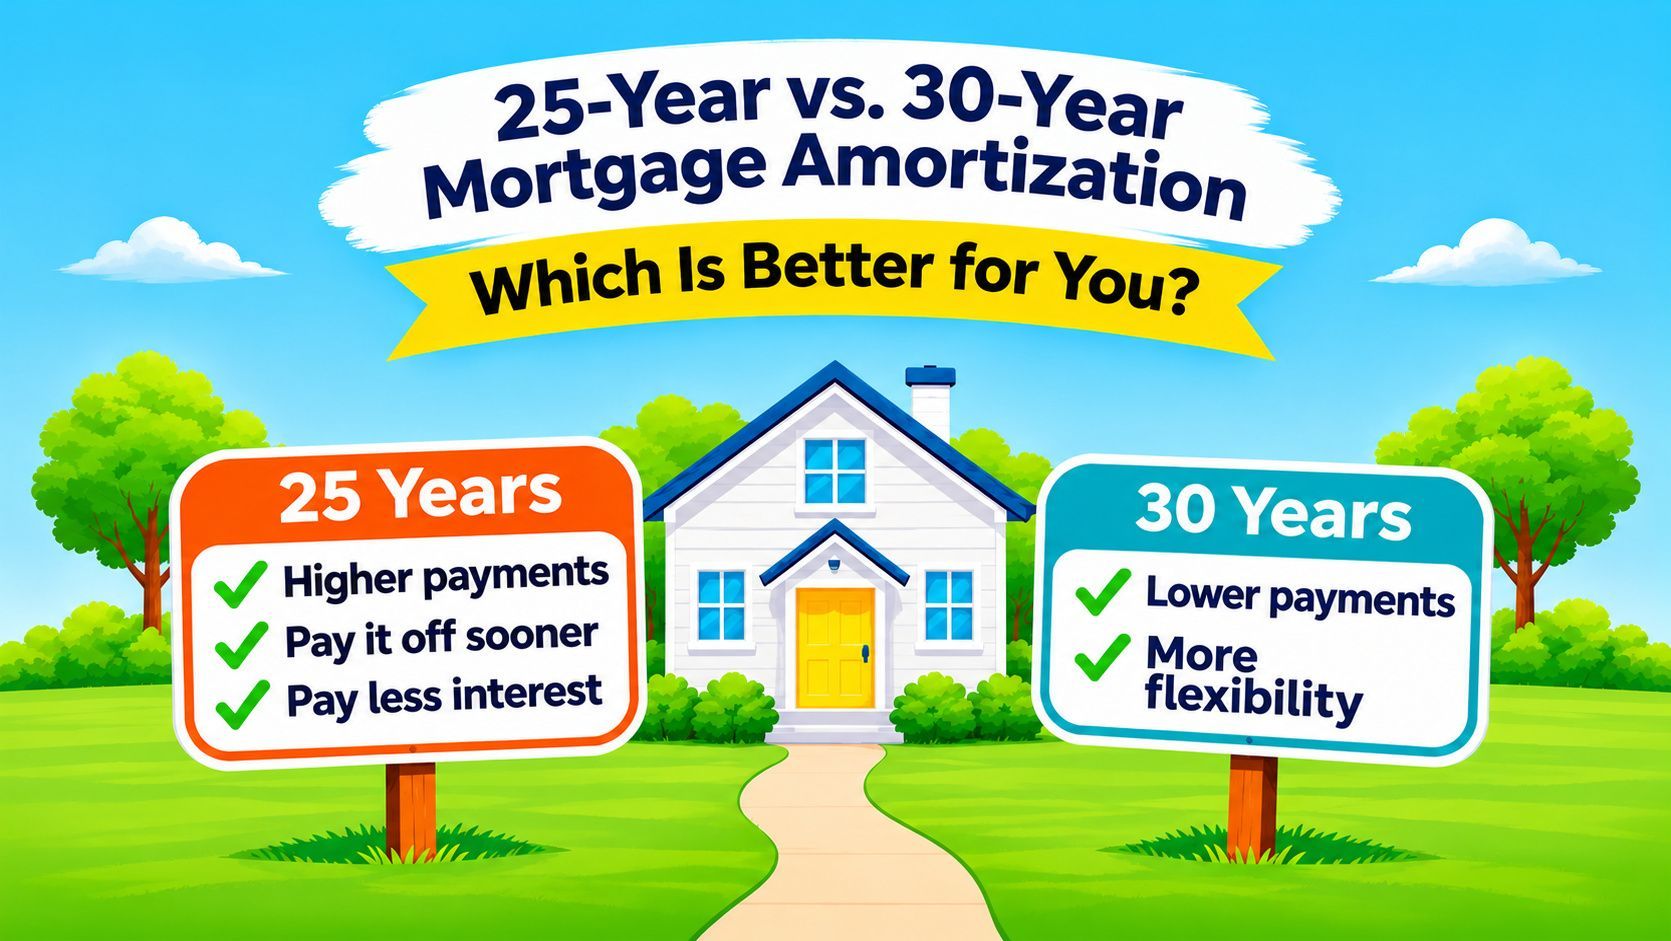
When it comes to mortgages, shorter isn't always better! You may have heard that a 25-year mortgage is better than a 30-year mortgage because you'll pay less interest. That's true, but there's more to consider! A shorter mortgage means higher monthly payments. A longer mortgage means lower payments, leaving more money for other things. So, which is better? It depends on your budget, lifestyle, and your future plans. What Is Mortgage Amortization? Amortization is the total time it would take to pay off your mortgage if you made all your regular payments. 25-year amortization: Higher payments, but you pay off your mortgage sooner and save on interest. 30-year amortization: Lower payments, but you take longer to pay off your mortgage and usually pay more interest. Let's Look at an Example: Imagine a $500,000 mortgage with a 4.5% interest rate.
For many Canadians, their home is their biggest financial asset. After years of homeownership, they may have paid off most (or all) or all their mortgage and built a lot of equity in their home. The problem: You can own a valuable home and still struggle to pay your monthly bills. You've probably heard the phrase “house rich and cash poor.” This is exactly what it means. For Canadian homeowners aged 55 and older, a reverse mortgage is one option worth looking at. It's definitely NOT the right solution for everyone. But for some homeowners, it can provide extra cash while allowing them to stay in the home they love. What Is a Reverse Mortgage? A reverse mortgage allows homeowners 55+ to access some of the equity in their home without selling it. Unlike a regular mortgage, you don't normally have to make monthly mortgage payments. Instead, interest is added to the amount you borrowed, so the balance grows over time. The mortgage is typically repaid when the home is sold, the homeowners permanently move out, or the last homeowner dies. And one of the biggest misconceptions I hear? The bank does NOT own your home. You do. You stay on title and continue to own your home. The money you receive is also generally tax-free because you're borrowing the money - it's not income. What Does “House Rich, Cash Poor” Look Like? Let's say you've lived in your home for 30 years. Your mortgage is paid off and your home is now worth $1 million. Sounds pretty good, right? But your retirement income may come from CPP, OAS, a pension and your savings. At the same time, groceries, property taxes, insurance, utilities and everything else seem to keep getting more expensive. So, while you may have hundreds of thousands of dollars in home equity, your monthly budget can still feel tight. You have the money. It's just tied up in your house. A reverse mortgage is one way to access some of that equity without having to sell and move. What Could You Use the Money For? There are generally no restrictions on how you use the money. Everyone's situation is different, but I've seen homeowners consider a reverse mortgage to: Pay off an existing mortgage, credit cards or other debts Add to your monthly retirement income Make home repairs or accessibility upgrades so you can stay in your home longer Pay for in-home care Help children or grandchildren financially Cover unexpected expenses or create an emergency fund Depending on the product, you may also have choices about how and when you receive the money. You don't necessarily have to take everything at once. Why Not Just Sell and Downsize? This is usually one of the first alternatives we talk about. Downsizing can make perfect sense—but it's not always as easy or as inexpensive as people think. A smaller home or condo can still be expensive, especially in many BC communities. Then add real estate commissions, legal fees, moving expenses, strata fees and other costs. And there's another part of this decision that has nothing to do with numbers. Your home is more than an asset on a balance sheet. Maybe you've lived there for 30 years. Your friends are nearby. You know your neighbours. Your doctor, family and community are close. Maybe you simply love your home and don't want to move. For many retirees, being able to stay in their home is an important part of their retirement plan. So... What's the Catch? There isn't any free money here. Reverse mortgage rates are typically higher than traditional mortgage rates. And because you aren't making regular mortgage payments, the interest gets added to the amount you borrowed. That means the amount you owe grows over time and the equity left in your home can decrease. There can also be appraisal, legal, setup and closing costs. Depending on the mortgage and when you repay it, there may also be a penalty. And remember—you still own the house. That means you're still responsible for maintaining it, keeping it insured and paying the property taxes. That's why it's important to look beyond the interest rate and understand the long-term costs. What About My Children's Inheritance? This is a conversation worth having with your family. A reverse mortgage will normally mean there is less equity left in your home for your estate. For some homeowners, leaving as much as possible to their children is extremely important. Others look at it differently. They would rather use some of the equity they've spent decades building to make their own retirement more comfortable. And some parents decide they'd rather help their children or grandchildren now , while they're still here to see them enjoy it (i.e. a gifted down payment). There's no right or wrong answer. It's your home, your equity and your decision. Reverse Mortgage or Home Equity Line of Credit (HELOC) ? A HELOC is another way to access the equity in your home. But there's an important difference. With a HELOC, you need enough income to qualify, and you'll need to make monthly payments. That can be difficult for someone who is retired and has a valuable home but limited monthly income. A reverse mortgage works differently because it's designed for older homeowners. One option isn't automatically better than the other. Maybe a HELOC makes more sense. Maybe refinancing makes more sense. Maybe a reverse mortgage does. It depends on your income, age, equity, monthly cash flow and, most importantly, what you're trying to accomplish. Is a Reverse Mortgage Right for You?