Reverse Mortgages in Canada: The Pros and Cons
Kelly Hudson • February 18, 2026

If you’re 55 or older and own your home, chances are you’ve heard about reverse mortgages.

  • Sometimes they’re described as a “retirement lifesaver.”
  • Other times they sound risky or confusing.


The truth? They’re neither magical nor terrible. They’re simply a financial tool — and like any tool, they work well in some situations and not so well in others – EDUCATION is the key!


Let’s break it down in plain English.


So… What Is a Reverse Mortgage?


A reverse mortgage allows you to borrow money against the value of your home — without making monthly mortgage payments.


Instead of you paying the lender every month, the interest gets added to the balance. The loan is typically repaid when:

  • The home is sold
  • You move out permanently
  • Or you pass away


In Canada, reverse mortgages are currently offered by:

  • HomeEquity Bank (CHIP Reverse Mortgage)
  • Equitable Bank
  • Bloom Financial


You still own your home and your name stays on title. That part often surprises people.


How It Works (Simple Version)


To qualify:

  • You must be 55 or older
  • You must own your home (you can still have a regular mortgage — it just needs to be paid out)
  • You can usually borrow up to about 55% of your home’s value (the older you are, the more you may qualify for)


You don’t make monthly payments.


But you must continue to:

  • Pay property taxes
  • Keep home insurance in place
  • Maintain the home


The money you receive is tax-free. It can come as:

  • A lump sum
  • Monthly advances
  • Or a combination of both


That flexibility is one reason many retirees like this option.


Why Do People Consider Reverse Mortgages?


Most of the homeowners I speak with aren’t looking for luxury spending money.


They’re trying to solve real life situations:

  • Covering rising living costs
  • Paying off debt before retirement
  • Managing health or care expenses
  • Staying in their home longer
  • Helping adult children with a down payment


For many Canadians, their house is their largest asset — but it doesn’t create monthly income. A reverse mortgage turns some of that home equity into usable cash.


The Pros (The Reasons People Like Them)


1. No Monthly Mortgage Payments

This is the big one.  If you’re living on CPP and OAS, removing a monthly mortgage payment can dramatically reduce stress. Cash flow improves immediately.


2. You Can Stay in Your Home

Most people I meet don’t want to move. They love their neighborhood. Their friends are nearby. Family visits often.  A reverse mortgage can allow you to age in place instead of selling before you’re ready.


3. The Money Is Tax-Free

Because it’s borrowed money — not income — it does not affect:

  • Old Age Security (OAS)
  • Guaranteed Income Supplement (GIS)


That’s a major advantage compared to withdrawing from investments.


There are no rules about spending.

  • Some clients use the funds to stay in place – health care at home.
  • Some clients renovate.
  • Some travel.
  • Some gift funds to children.
  • Some simply create a safety cushion.


It’s your equity – you decide.


5. You Keep Ownership

The bank does not own your home.


As long as you live in your home, maintain it, insure it, and pay property taxes — you own your home and can stay.


6. No Negative Equity Guarantee

In Canada, reverse mortgages include protection so that you (or your estate) will never owe more than the home is worth — even if property values decline.


That protection matters.


The Cons (And Yes, There Are Some)

Reverse mortgages are not cheap money.


1. Higher Interest Rates

Rates are typically higher than traditional mortgages.


Why? Because the lender may wait many years to be repaid and there are no monthly payments coming in. Over time, that interest compounds.


2. The Loan Balance Grows

Since you’re not making payments:

  • Interest is added to the balance
  • The amount owed increases each year


That means your remaining home equity decreases over time.


If leaving a debt-free home to children is extremely important to you, this needs careful discussion.


3. Setup Costs

There can be:

  • Appraisal fees
  • Legal fees
  • Administrative costs


Often these are rolled into the mortgage, but they still reduce equity.


4. It’s Meant to Be Long-Term

Reverse mortgages work best when you plan to stay in the home for many years.


If you sell shortly after setting one up, the costs and interest may not make sense.


5. You Still Have Responsibilities

You must:

  • Maintain the property
  • Pay property taxes
  • Keep insurance active


If those obligations aren’t met, the lender can require repayment.


Let’s Clear Up a Few Myths

  • “The bank will own my house.”
  • No. You remain on title.
  • “My kids will inherit the debt.”
  • No. The loan is repaid from the home’s value — not from your children personally.
  • “I could be forced out.”
  • Not if you follow the terms of the agreement.


Who Might A Reverse Mortgage Make Sense For?
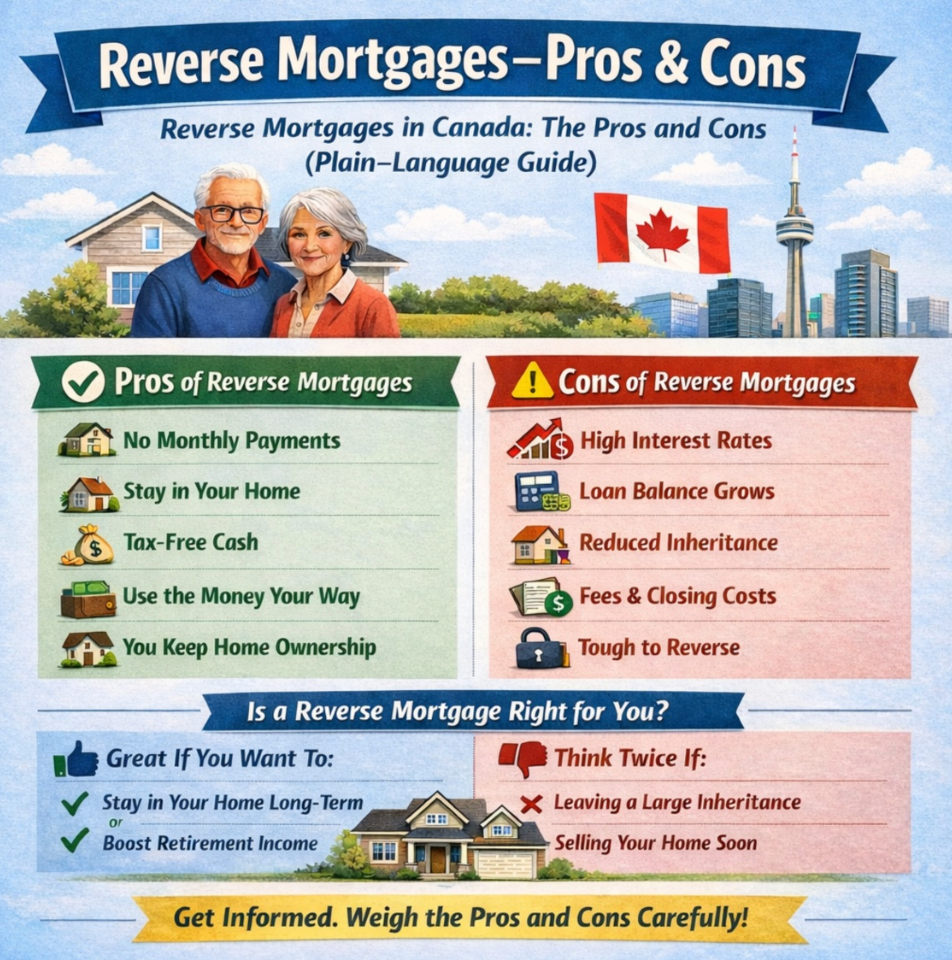

A reverse mortgage can be a smart solution if:

  • You own your home
  • You plan to stay in your home long term
  • You need additional retirement cash flow
  • You don’t qualify for traditional refinancing
  • You understand the long-term cost


It may not be ideal if:

  • You have cheaper borrowing options available
  • You plan to move in a few years
  • Leaving maximum equity to heirs is your top priority


My Professional Opinion


I don’t see reverse mortgages as “good” or “bad.”


I see them as strategic.  In the right situation, they can:

  • Reduce stress
  • Improve retirement lifestyle
  • Provide breathing room


In the wrong situation, they can erode your homes equity faster than expected.


That’s why education matters.  It’s also why I always encourage:

  • A family conversation
  • A long-term cost review
  • A full comparison against other options


A reverse mortgage should never be a last-minute decision made under pressure.


Kelly’s Final Thoughts


Your home is more than an investment. It’s security, comfort, and often decades of memories.


If you’re considering accessing that equity, let’s make sure the plan fits your long-term goals — not just today’s cash flow.


If you’d like to talk through your personal scenario, I’m happy to help.


Warmly,

Kelly Hudson
Mortgage Broker & Reverse Mortgage Specialist
604-312-5009
Kelly@KellyHudsonMortgages.com
www.KellyHudsonMortgages.com
Kelly Hudson
MORTGAGE ARCHITECTS
RECENT POSTS 

Graphic comparing 25-year vs. 30-year mortgage amortization with house and pros/cons lists
By Kelly Hudson • November 3, 2026
When it comes to mortgages, shorter isn't always better! You may have heard that a 25-year mortgage is better than a 30-year mortgage because you'll pay less interest. That's true, but there's more to consider! A shorter mortgage means higher monthly payments. A longer mortgage means lower payments, leaving more money for other things. So, which is better? It depends on your budget, lifestyle, and your future plans. What Is Mortgage Amortization? Amortization is the total time it would take to pay off your mortgage if you made all your regular payments. 25-year amortization: Higher payments, but you pay off your mortgage sooner and save on interest. 30-year amortization: Lower payments, but you take longer to pay off your mortgage and usually pay more interest. Let's Look at an Example: Imagine a $500,000 mortgage with a 4.5% interest rate. 
Reverse mortgage ad with smiling couple, house, flowers, and question marks about using home equity
By Kelly Hudson • October 9, 2026
For many Canadians, their home is their biggest financial asset. After years of homeownership, they may have paid off most (or all) or all their mortgage and built a lot of equity in their home. The problem: You can own a valuable home and still struggle to pay your monthly bills. You've probably heard the phrase “house rich and cash poor.” This is exactly what it means. For Canadian homeowners aged 55 and older, a reverse mortgage is one option worth looking at. It's definitely NOT the right solution for everyone. But for some homeowners, it can provide extra cash while allowing them to stay in the home they love. What Is a Reverse Mortgage? A reverse mortgage allows homeowners 55+ to access some of the equity in their home without selling it. Unlike a regular mortgage, you don't normally have to make monthly mortgage payments. Instead, interest is added to the amount you borrowed, so the balance grows over time. The mortgage is typically repaid when the home is sold, the homeowners permanently move out, or the last homeowner dies. And one of the biggest misconceptions I hear? The bank does NOT own your home. You do. You stay on title and continue to own your home. The money you receive is also generally tax-free because you're borrowing the money - it's not income. What Does “House Rich, Cash Poor” Look Like? Let's say you've lived in your home for 30 years. Your mortgage is paid off and your home is now worth $1 million. Sounds pretty good, right? But your retirement income may come from CPP, OAS, a pension and your savings. At the same time, groceries, property taxes, insurance, utilities and everything else seem to keep getting more expensive. So, while you may have hundreds of thousands of dollars in home equity, your monthly budget can still feel tight. You have the money. It's just tied up in your house. A reverse mortgage is one way to access some of that equity without having to sell and move. What Could You Use the Money For? There are generally no restrictions on how you use the money. Everyone's situation is different, but I've seen homeowners consider a reverse mortgage to: Pay off an existing mortgage, credit cards or other debts Add to your monthly retirement income Make home repairs or accessibility upgrades so you can stay in your home longer Pay for in-home care Help children or grandchildren financially Cover unexpected expenses or create an emergency fund Depending on the product, you may also have choices about how and when you receive the money. You don't necessarily have to take everything at once. Why Not Just Sell and Downsize? This is usually one of the first alternatives we talk about. Downsizing can make perfect sense—but it's not always as easy or as inexpensive as people think. A smaller home or condo can still be expensive, especially in many BC communities. Then add real estate commissions, legal fees, moving expenses, strata fees and other costs. And there's another part of this decision that has nothing to do with numbers. Your home is more than an asset on a balance sheet. Maybe you've lived there for 30 years. Your friends are nearby. You know your neighbours. Your doctor, family and community are close. Maybe you simply love your home and don't want to move. For many retirees, being able to stay in their home is an important part of their retirement plan. So... What's the Catch? There isn't any free money here. Reverse mortgage rates are typically higher than traditional mortgage rates. And because you aren't making regular mortgage payments, the interest gets added to the amount you borrowed. That means the amount you owe grows over time and the equity left in your home can decrease. There can also be appraisal, legal, setup and closing costs. Depending on the mortgage and when you repay it, there may also be a penalty. And remember—you still own the house. That means you're still responsible for maintaining it, keeping it insured and paying the property taxes. That's why it's important to look beyond the interest rate and understand the long-term costs. What About My Children's Inheritance? This is a conversation worth having with your family. A reverse mortgage will normally mean there is less equity left in your home for your estate. For some homeowners, leaving as much as possible to their children is extremely important. Others look at it differently. They would rather use some of the equity they've spent decades building to make their own retirement more comfortable. And some parents decide they'd rather help their children or grandchildren now , while they're still here to see them enjoy it (i.e. a gifted down payment). There's no right or wrong answer. It's your home, your equity and your decision. Reverse Mortgage or Home Equity Line of Credit (HELOC) ? A HELOC is another way to access the equity in your home. But there's an important difference. With a HELOC, you need enough income to qualify, and you'll need to make monthly payments. That can be difficult for someone who is retired and has a valuable home but limited monthly income. A reverse mortgage works differently because it's designed for older homeowners. One option isn't automatically better than the other. Maybe a HELOC makes more sense. Maybe refinancing makes more sense. Maybe a reverse mortgage does. It depends on your income, age, equity, monthly cash flow and, most importantly, what you're trying to accomplish. Is a Reverse Mortgage Right for You?