Title Insurance: What Every BC Home Buyer Should Know!

Kelly Hudson • March 16, 2023

You found your new home—congratulations! It’s your biggest asset and one of the most important investments you’ll ever make. How will you keep it safe?


When you get a mortgage in BC, one part of your closing costs will be title insurance. The premium is a one-time charge, and the policy protects the lender.

  • You also can purchase owner’s title insurance to protect yourself, but it’s optional.


Title insurance is NOT home insurance.


Here’s what you need to know about what title insurance.


Title insurance is a policy that covers third-party claims on a property that don’t show up in the initial title

search and arise after a real estate closing.

  • A third party is someone other than the property’s owner, such as a construction company that

didn’t get paid for its work on the home under a previous owner.

  • The term “title” refers to someone’s legal ownership of the property.


A title claim could arise at any time, even after you’ve owned the property with no problems for many years. How could this happen? Someone else might have ownership rights that you don’t know about when you make an offer to buy a property. Even the current owner might not be aware that someone else has a claim on the property. In the case of an overlooked heir, even the person who has those rights might not know they have them.


Before your home mortgage closes, your mortgage lender will order a title search from a title company. The title company searches for public records related to your home to try to find any title defects that could affect the lender’s or buyer’s property rights such as:


  • Liens can get placed on the property by a contractor, tax authority or lender who hasn’t been paid. You don’t want to get stuck paying a previous owner’s unpaid bills.
  • Easements are someone else’s right to use your property even though you are the owner. For example, if there are utility lines in your backyard, the utility company will have an easement that allows them to access your property if they need to work on the lines. The easement could limit your ability to use your property however you want.
  • Encumbrances include liens (also called “financial encumbrances”) as well as easements, but also include zoning laws & restrictive covenants.
  • A title company searches public records including deeds, mortgages, divorce decrees, court judgments, tax records and child support orders. 


What Does Title Insurance Cover?


A title insurance policy covers underlying issues with a property’s title that might have been missed before you bought the home. Basically, it comes in handy if the public record search conducted by the titled company failed to catch any liens or ownership disputes.


Residential title insurance can protect you against issues that could affect your ability to sell, lease or mortgage your property. It can provide coverage for the following:


  • An unforeseen defect in your title ownership.
  • Negligence or errors made by your lawyer relating to title risks.
  • Unpaid utilities, mortgages, taxes or condo/strata maintenance fees – these are known as liens.
  • Fraud, survey or records errors.
  • A pre-existing outbuilding that must be removed because it encroaches on a neighbouring property.
  • The gap period between when a property purchase is finalized or closed and when the title is officially registered with the government.


The BC Land Title Registration Office does not require title insurance because they guarantee the

title to your property.

  • However, your lender may require it as a condition of your mortgage.


Q. There are 2 types of Title insurance. What is the difference between a Lender Policy and an

Owner Policy?


A lender’s title insurance policy protects the organization (lender) from which you obtained your mortgage

loan.

  • For example, if you default on your mortgage repayments as a direct result of the title defect, the lender will be protected from that loss.


An owner’s title insurance policy protects you from potential loss.

  • For example, if it becomes clear that someone else is the true titleholder of the property, the policy will cover your loss.


Who Pays for Title Insurance?


The buyer pays for the lender’s title insurance policy as part of their closing costs. Although title insurance costs range between $200 - $400, prices vary based on various factors.

  • The value of your home, insurance provider and province you live in will all affect the cost of your one-time fee.


Key Takeaway


Title insurance is a type of insurance that protects the lender (and if purchased, the property owner) against loss or damage caused by problems with the title to the land.

  • In BC, typically all Lenders require Title Insurance as a condition of you receiving their mortgage.
Kelly Hudson
MORTGAGE ARCHITECTS
RECENT POSTS 

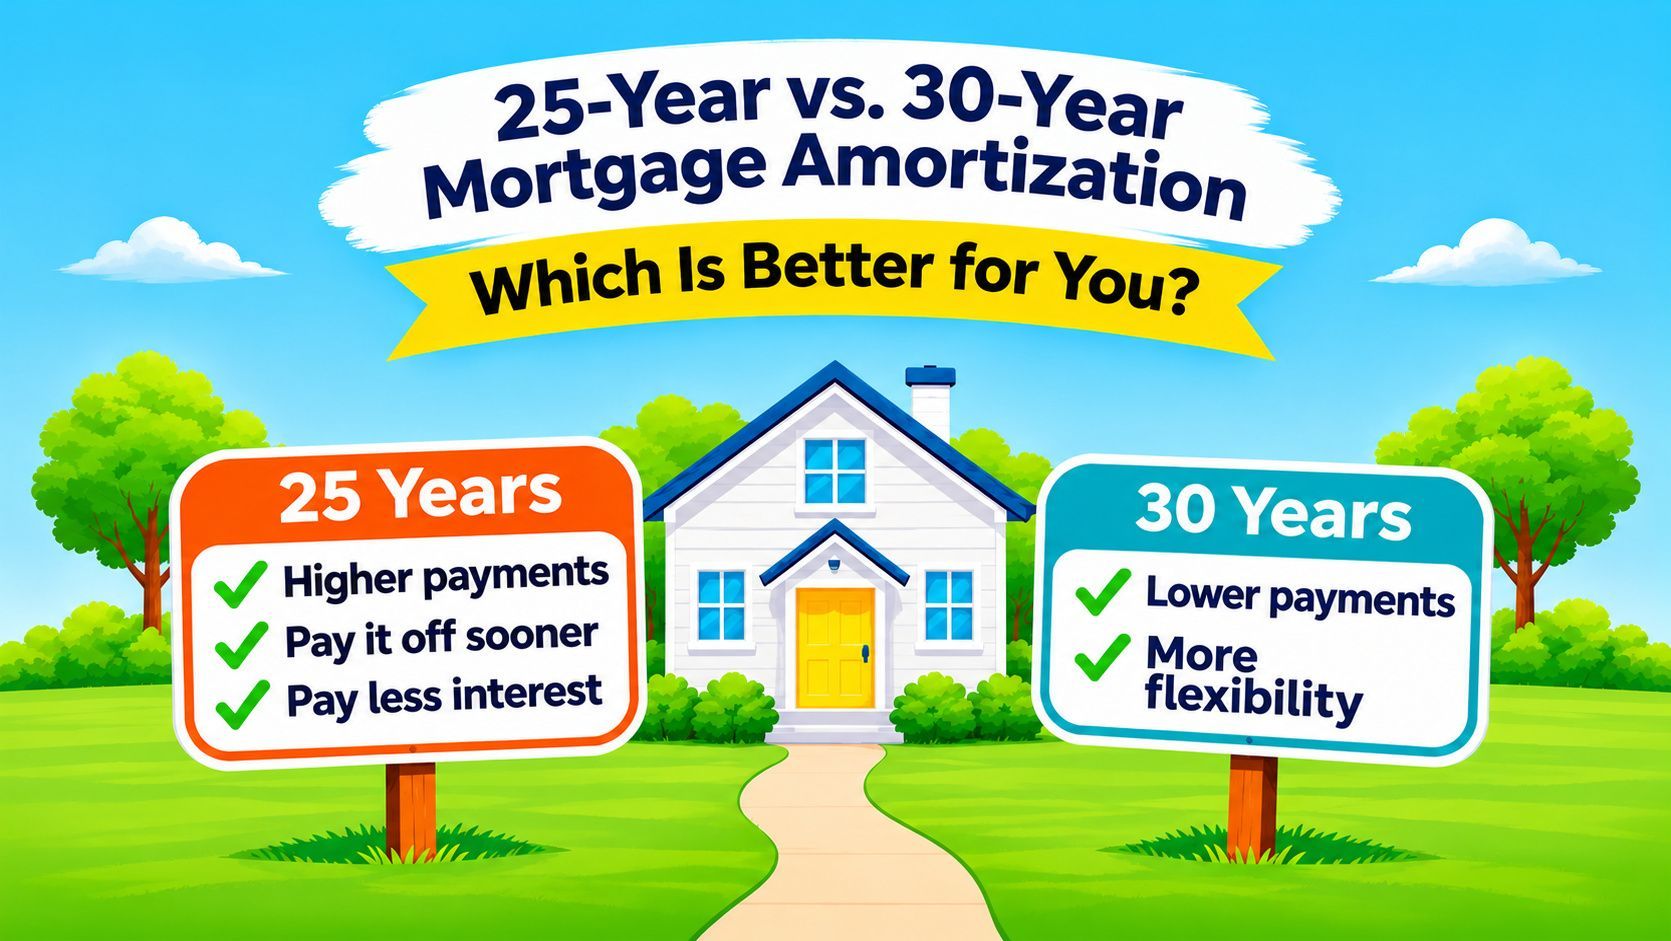
Graphic comparing 25-year vs. 30-year mortgage amortization with house and pros/cons lists
By Kelly Hudson • November 3, 2026
When it comes to mortgages, shorter isn't always better! You may have heard that a 25-year mortgage is better than a 30-year mortgage because you'll pay less interest. That's true, but there's more to consider! A shorter mortgage means higher monthly payments. A longer mortgage means lower payments, leaving more money for other things. So, which is better? It depends on your budget, lifestyle, and your future plans. What Is Mortgage Amortization? Amortization is the total time it would take to pay off your mortgage if you made all your regular payments. 25-year amortization: Higher payments, but you pay off your mortgage sooner and save on interest. 30-year amortization: Lower payments, but you take longer to pay off your mortgage and usually pay more interest. Let's Look at an Example: Imagine a $500,000 mortgage with a 4.5% interest rate. 
Reverse mortgage ad with smiling couple, house, flowers, and question marks about using home equity
By Kelly Hudson • October 9, 2026
For many Canadians, their home is their biggest financial asset. After years of homeownership, they may have paid off most (or all) or all their mortgage and built a lot of equity in their home. The problem: You can own a valuable home and still struggle to pay your monthly bills. You've probably heard the phrase “house rich and cash poor.” This is exactly what it means. For Canadian homeowners aged 55 and older, a reverse mortgage is one option worth looking at. It's definitely NOT the right solution for everyone. But for some homeowners, it can provide extra cash while allowing them to stay in the home they love. What Is a Reverse Mortgage? A reverse mortgage allows homeowners 55+ to access some of the equity in their home without selling it. Unlike a regular mortgage, you don't normally have to make monthly mortgage payments. Instead, interest is added to the amount you borrowed, so the balance grows over time. The mortgage is typically repaid when the home is sold, the homeowners permanently move out, or the last homeowner dies. And one of the biggest misconceptions I hear? The bank does NOT own your home. You do. You stay on title and continue to own your home. The money you receive is also generally tax-free because you're borrowing the money - it's not income. What Does “House Rich, Cash Poor” Look Like? Let's say you've lived in your home for 30 years. Your mortgage is paid off and your home is now worth $1 million. Sounds pretty good, right? But your retirement income may come from CPP, OAS, a pension and your savings. At the same time, groceries, property taxes, insurance, utilities and everything else seem to keep getting more expensive. So, while you may have hundreds of thousands of dollars in home equity, your monthly budget can still feel tight. You have the money. It's just tied up in your house. A reverse mortgage is one way to access some of that equity without having to sell and move. What Could You Use the Money For? There are generally no restrictions on how you use the money. Everyone's situation is different, but I've seen homeowners consider a reverse mortgage to: Pay off an existing mortgage, credit cards or other debts Add to your monthly retirement income Make home repairs or accessibility upgrades so you can stay in your home longer Pay for in-home care Help children or grandchildren financially Cover unexpected expenses or create an emergency fund Depending on the product, you may also have choices about how and when you receive the money. You don't necessarily have to take everything at once. Why Not Just Sell and Downsize? This is usually one of the first alternatives we talk about. Downsizing can make perfect sense—but it's not always as easy or as inexpensive as people think. A smaller home or condo can still be expensive, especially in many BC communities. Then add real estate commissions, legal fees, moving expenses, strata fees and other costs. And there's another part of this decision that has nothing to do with numbers. Your home is more than an asset on a balance sheet. Maybe you've lived there for 30 years. Your friends are nearby. You know your neighbours. Your doctor, family and community are close. Maybe you simply love your home and don't want to move. For many retirees, being able to stay in their home is an important part of their retirement plan. So... What's the Catch? There isn't any free money here. Reverse mortgage rates are typically higher than traditional mortgage rates. And because you aren't making regular mortgage payments, the interest gets added to the amount you borrowed. That means the amount you owe grows over time and the equity left in your home can decrease. There can also be appraisal, legal, setup and closing costs. Depending on the mortgage and when you repay it, there may also be a penalty. And remember—you still own the house. That means you're still responsible for maintaining it, keeping it insured and paying the property taxes. That's why it's important to look beyond the interest rate and understand the long-term costs. What About My Children's Inheritance? This is a conversation worth having with your family. A reverse mortgage will normally mean there is less equity left in your home for your estate. For some homeowners, leaving as much as possible to their children is extremely important. Others look at it differently. They would rather use some of the equity they've spent decades building to make their own retirement more comfortable. And some parents decide they'd rather help their children or grandchildren now , while they're still here to see them enjoy it (i.e. a gifted down payment). There's no right or wrong answer. It's your home, your equity and your decision. Reverse Mortgage or Home Equity Line of Credit (HELOC) ? A HELOC is another way to access the equity in your home. But there's an important difference. With a HELOC, you need enough income to qualify, and you'll need to make monthly payments. That can be difficult for someone who is retired and has a valuable home but limited monthly income. A reverse mortgage works differently because it's designed for older homeowners. One option isn't automatically better than the other. Maybe a HELOC makes more sense. Maybe refinancing makes more sense. Maybe a reverse mortgage does. It depends on your income, age, equity, monthly cash flow and, most importantly, what you're trying to accomplish. Is a Reverse Mortgage Right for You?