Getting a Mortgage After Separation or Divorce in Canada: What You Need to Know
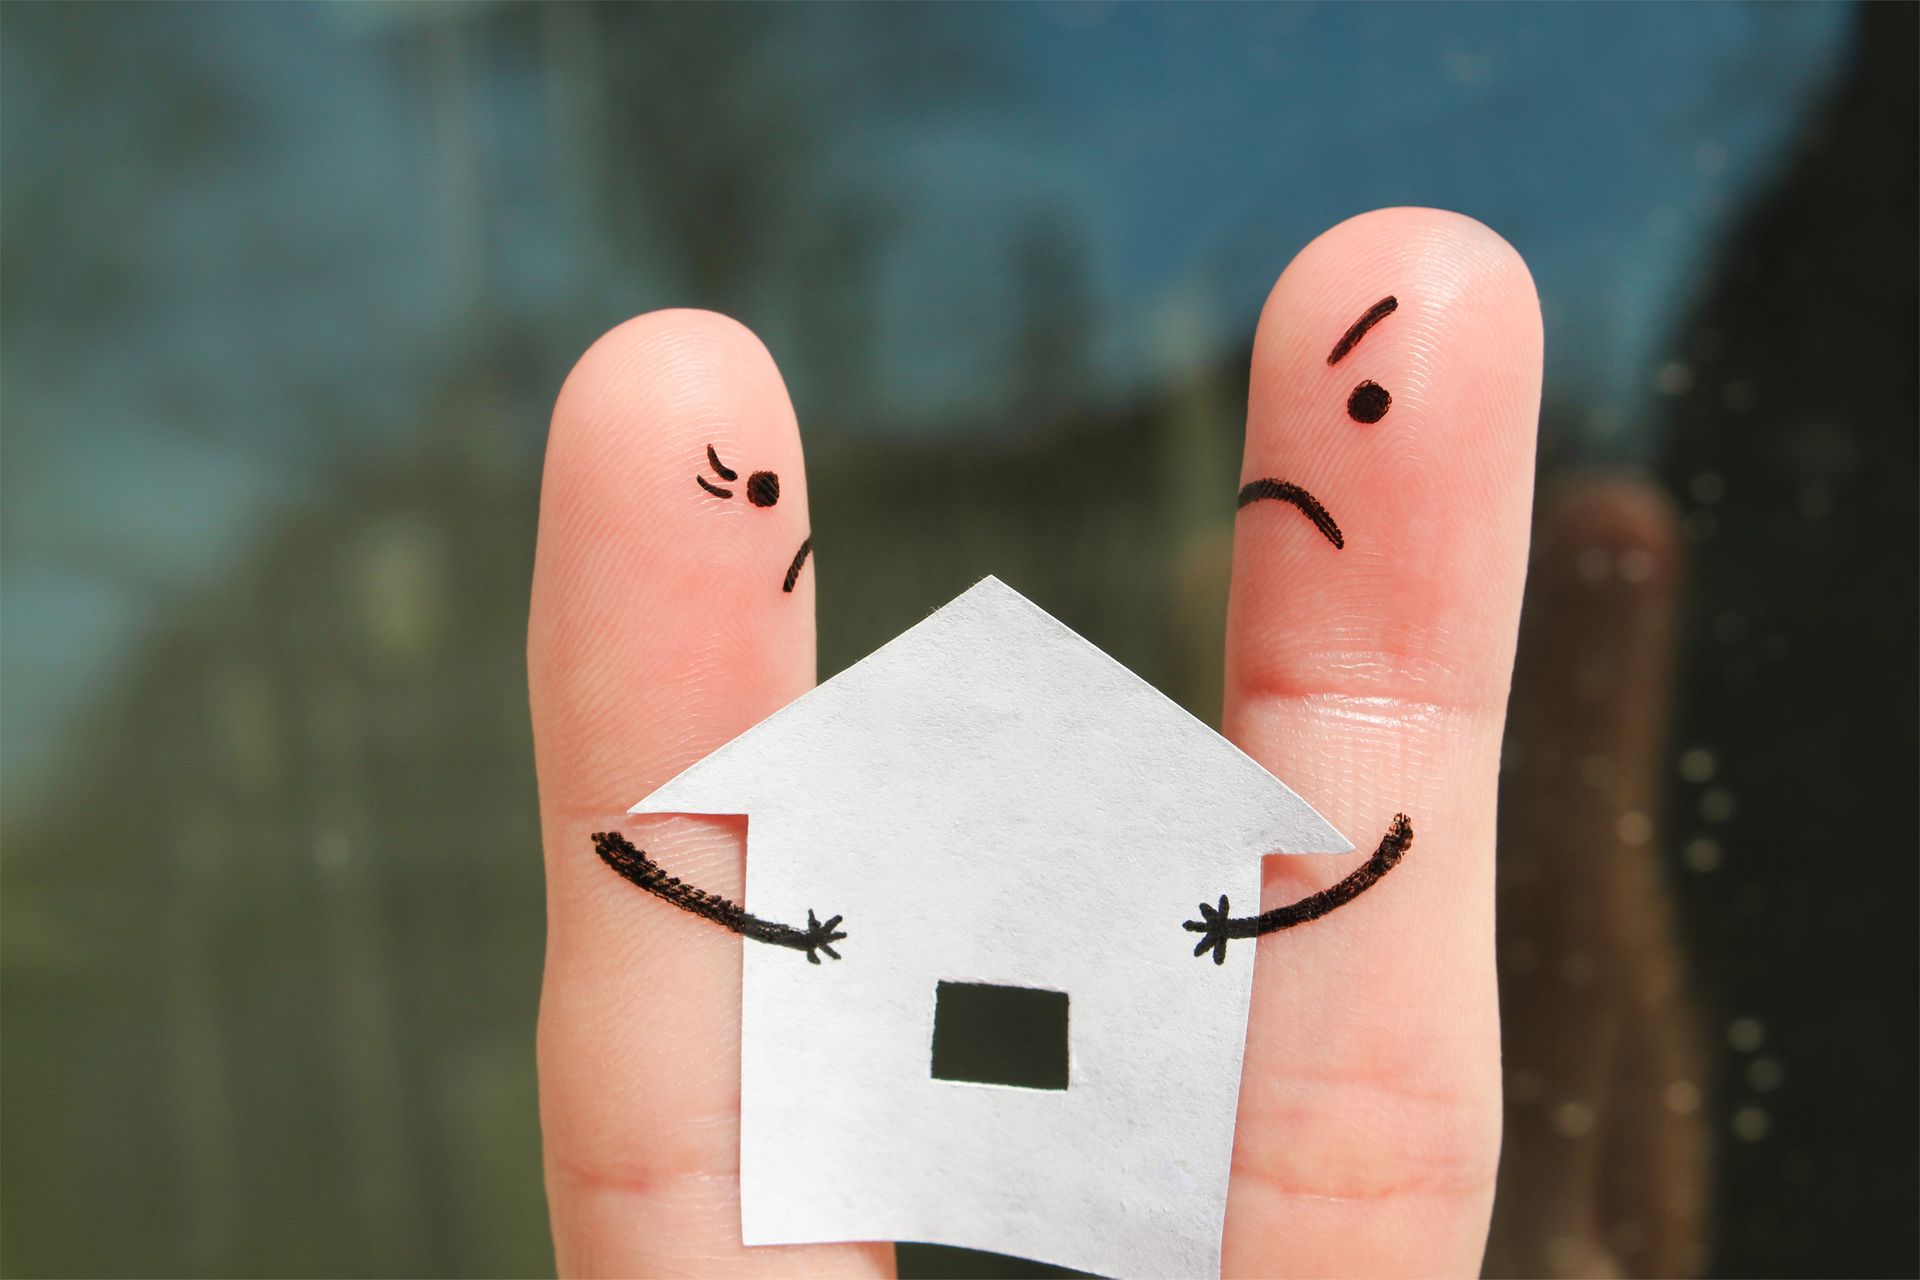
Separation and divorce are major life events that significantly impact finances—including homeownership. In Canada, approximately 40% of marriages end in divorce, making it a common challenge for homeowners.
As a mortgage broker, I work with many clients who are navigating the challenges of
keeping or selling their home, refinancing, or qualifying for a new mortgage post-separation.
Lenders assess these applications differently than standard ones, particularly when it comes to
income, debts, and liabilities. Whether you want to stay in your current home or move on to a new one, understanding your mortgage options is essential.
How Separation & Divorce Impact Your Mortgage
When separating from a spouse, one of the biggest financial decisions is what to do with the family home. Here are some common scenarios:
1. Keeping the Home
If one spouse wants to stay in the home, they must refinance the mortgage to remove the other person’s name from title and buy out their ex’s share of the equity.
2. Selling the Home
In some cases, selling the home and splitting the proceeds is the best financial option. This provides a clean break but requires both parties to qualify for new mortgages if they wish to buy separate homes.
3. Co-Owning After Separation
Some ex-partners choose to co-own the home for a period, often for the sake of stability for children. While this may work temporarily, it will complicate future borrowing power.
4. Existing Mortgage Responsibilities
Even if a separation agreement states that one party is responsible for the mortgage, lenders will still consider both parties liable unless the mortgage is refinanced and the ex’s name is removed from the title & the mortgage.
Important: If both names remain on the mortgage and your ex stops making payments,
your credit score and future borrowing ability will be affected.
Mortgage Options After Separation or Divorce
1. Refinancing your Mortgage to Keep the Home
To stay in the home, you will need to refinance the mortgage in your name alone (OR adding a co-signer). This involves:
Qualifying based on your income and credit score
Paying out your ex-spouse’s share of the equity
Removing your ex-spouse from the mortgage and title
If the home has increased in value, a refinance may allow you to access additional equity to cover legal fees or consolidate debts.
BLOG Would a Co-Signer Enable You to Qualify for a Mortgage?
2. Spousal Buyout Program
For those who need to buy out their spouse’s share but don’t have a large down payment, some lenders offer a Spousal Buyout Program that allows refinancing up to 95% of the home’s value instead of the usual 80%.
Requirements for a Spousal Buyout Mortgage:
✅ The home must be the primary residence.
✅
A legal separation agreement must be in place.
✅ The funds can only be used to pay the spouse’s equity and joint debts.
✅ You must have enough income to qualify for the new mortgage.
This option can help one partner keep the home without a massive cash outlay upfront.
BLOG If Your Marriage is Ending and You Want to Keep the Family Home, Consider a Spousal Buyout
3. Purchasing a New Home After Separation
If you decide to sell and buy a new home, you’ll need to qualify for a mortgage based on your individual income, debts, and credit score.
🔹 Key considerations for getting a new mortgage:
You’ll need at least a 5% down payment.
Lenders will assess your debt-to-income ratio, including any spousal or child support obligations.
If you’re receiving support, some lenders will count it as income—provided it’s documented in a legal agreement, and you can prove there is a history of receiving payments.
4. Alternative Lenders for Challenging Situations
If you don’t meet traditional mortgage requirements due to:
❌ A low credit score
❌ High debt from the divorce
❌ Hard to prove/ unstable/low income
…you might consider
alternative lenders. These lenders have more flexible criteria and may accept lower credit scores or higher debt ratios. However, interest rates will be higher due to the increased risk for the lender.
Steps to Take Before Applying for a Mortgage
If you’re considering a mortgage after separation or divorce, here’s how to prepare:
1. Get a Legal Separation Agreement
Lenders require a formal signed separation agreement outlining property division, spousal/child support payments, and financial responsibilities. Without this document, getting a mortgage approval will be extremely difficult, especially if there are children.
2. Check Your Credit Report
Separation can impact your credit, especially if joint debts aren’t handled properly. Contact Equifax or TransUnion to get a copy of your credit report to check for any missed payments or joint accounts that need to be closed.
BLOG 8 Credit Rules You Need to Know, Before You Buy a Home
3. Close or Refinance Joint Debts
Even if your separation agreement assigns a debt to your ex-spouse, lenders still see it as your responsibility UNTIL your name is removed from the account. Work on:
Paying off or refinancing joint debts into separate accounts.
Closing shared credit cards or lines of credit.
4. Start Working With a Mortgage Broker Early
The earlier you consult a mortgage broker, the better your chances of securing financing that fits your new financial reality. A broker can:
✅ Assess your
borrowing power based on your new financial situation.
✅ Find lenders who consider any
spousal/child support payments as income.
✅ Help improve your
credit and debt positioning before applying.
5. Save for a Down Payment
If you plan to purchase a new home, start saving for a down payment as soon as possible. If you are receiving equity from the sale of a home or a spousal buyout, set aside a portion for this purpose.
Final Thoughts: Moving Forward with Confidence
Divorce and separation can bring financial uncertainty, but they don’t have to derail your homeownership goals. Whether you’re keeping
your current home, buying a new one, or refinancing, understanding your mortgage options is key to making informed financial decisions.
As a mortgage broker, I can help you:
🔹 Navigate mortgages options tailored to your
new financial situation.
🔹 Secure the
best rates and terms for your new mortgage
🔹 Ensure a smooth transition into your next chapter of homeownership.
If you or someone you know is going through a separation or divorce and needs mortgage advice, let’s get connected. A well-planned mortgage strategy can help you move forward with financial confidence.
As you can tell there is a lot to discuss, let’s have a chat and find a mortgage that works for you.
Kelly Hudson
Mortgage Expert
Mortgage Architects – A Better Way
Mobile: 604-312-5009
Kelly@KellyHudsonMortgages.com
www.KellyHudsonMortgages.com